Balloon Payments Explained: Are They Worth the Risk for Your Next Car?
Buying a car is exciting, but the financing details can be confusing. One option that often looks attractive at first glance is the balloon payment car deal. Lower monthly payments, a newer car, and a quick approval can seem like an easy yes.
But behind those low monthly numbers sits a large final payment: the balloon. Understanding how this works is essential before you sign anything. A balloon deal can be useful in some situations, but it can also become a serious financial trap if you are not prepared.
What Is a Balloon Payment on a Car Loan?
A balloon payment is a large lump sum owed at the end of your car finance agreement. Instead of paying off the full cost of the car through regular monthly payments, you pay smaller amounts each month and then one big payment at the end.
Here is the basic idea: the lender defers a portion of the car’s cost to the end of the contract. This deferred amount is the “balloon”. Your monthly payments are calculated as if you will pay off only part of the car during the term, leaving the balloon to be settled later.
At the end of the agreement, you generally have three options:
- Pay the balloon amount in full and keep the car
- Refinance the balloon and continue paying monthly
- Sell or trade in the car and use the value to cover the balloon
On paper, this gives you flexibility. In reality, it means you must plan in advance for a substantial final cost.
How Balloon Payments Change Your Monthly Costs
Balloon deals are popular because they make monthly car payments lower than on a standard loan. This can be very appealing if you are working with a tight monthly budget or want to drive a more expensive car than you could otherwise afford.
Compare a simple example:
| Feature | Standard Car Loan | Balloon Payment Loan |
|---|---|---|
| Car price | $30,000 | $30,000 |
| Term | 5 years | 5 years |
| Balloon amount | $0 | $9,000 (30%) |
| Monthly repayment | Higher | Lower |
| Final payment | $0 (already paid) | $9,000 balloon due |
While the exact figures depend on interest rates, you can see the trade‑off: you save on monthly cash flow, but you must eventually deal with a large lump sum.
The Real Risks Behind Balloon Car Finance
Balloon payments are not automatically bad, but they are often misunderstood. The main dangers appear when life does not go according to plan, or when buyers focus only on the monthly cost and ignore the long‑term picture.
Key risks include:
- Underestimating the final balloon and being unable to pay it
- Needing to refinance at a higher interest rate
- Owing more than the car is worth if its value drops
- Feeling forced to sell or trade in when you would rather keep the car
If your income falls, expenses rise, or interest rates climb, that balloon can be very difficult to manage. What looked like a flexible option can become a financial burden you are scrambling to escape.
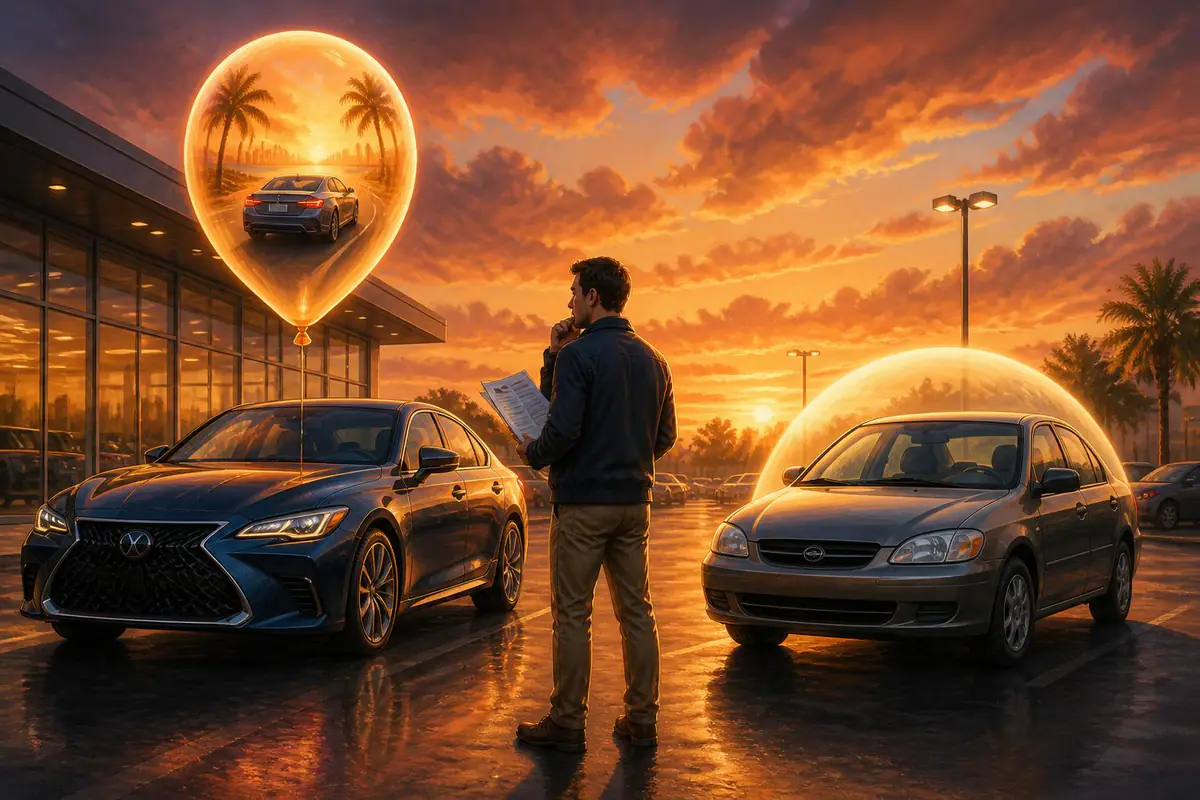
There is also a psychological risk: lower monthly payments can tempt you into buying more car than you can afford. You may choose a higher‑priced model because it “fits” your monthly budget, forgetting that the balloon at the end will be much larger too.
When a Balloon Payment Can Make Sense
Despite the risks, balloon deals can make sense in specific situations. The key is to be brutally honest about your finances and your future plans.
You might reasonably consider a balloon payment if:
You have a predictable future lump sum. For example, you know you will receive a bonus, an inheritance, or the maturity of an investment around the time the balloon is due. In this case, the structure may match your cash‑flow reality.
Your income is temporarily lower but likely to rise in the near future. Perhaps you are finishing a professional qualification or starting a new career. You can handle smaller payments now and expect to refinance or pay the balloon more comfortably later.
You change cars regularly. If you typically trade in your car every three years and are disciplined about mileage and maintenance, you may plan to use the car’s value to cover the balloon, then start a new agreement. Even then, you must be sure you are not rolling hidden debt into each new deal.
Warning Signs a Balloon Deal Is Too Risky for You
Sometimes, the clearest decision is to walk away. If you notice these warning signs, a balloon payment is probably not right for your next car:
- You cannot explain exactly how you will pay the balloon
- Your budget is already tight with no emergency savings
- You are stretching to afford a more expensive car
- You tend to use credit to cover unexpected costs
If any of these sound familiar, you may be taking on too much financial uncertainty. A simpler loan or even a more affordable car could be a safer, less stressful choice.
Practical Steps Before You Sign a Balloon Agreement
Before committing to a balloon payment, walk through these practical steps. They will help you move from impulse to informed decision.
1. Run the full‑term numbers
Ask the lender for a clear breakdown of:
total interest over the life of the loan, the exact balloon amount, and what your car will have cost you in total if you keep it. Compare this to a standard loan for the same car. Many buyers are surprised to see that lower monthly payments can mean paying much more interest overall.
2. Stress‑test your budget
Create a simple budget that includes your current income, essential expenses, savings goals, and the proposed monthly car payment. Then ask yourself:
What happens if interest rates rise when I want to refinance? What if my income drops by 10–20%? Could I still manage the payments or save for the balloon? Being conservative now protects you from stress later.
3. Plan your exit strategy today
Decide in advance how you will handle the end of the deal. Will you:
Save monthly into a separate account to build the balloon amount? Intend to sell or trade the car before the balloon is due? Expect to refinance the balloon on new terms?
Write this plan down. If you cannot describe a realistic strategy, the deal is too risky.
4. Consider a cheaper car or longer term
Sometimes, the real solution is not clever financing but a more modest vehicle choice. A slightly older or less luxurious model may allow you to use a straightforward loan with affordable payments and no balloon at all.
If your priority is a stable, predictable budget, it is usually better to choose the simplest structure you can comfortably afford rather than the fanciest car you can technically finance.
So, Are Balloon Payments Worth the Risk?
The honest answer: balloon payments are a tool, not a miracle. They are worth considering only if you fully understand them, have a specific plan for the final payment, and are disciplined about your overall finances.
They may be suitable if you:
have a clear future lump sum, expect rising income, or regularly change cars and manage your mileage and maintenance carefully.
They are likely too risky if you:
are already stretched, have no savings buffer, or are tempted to use them just to drive a car beyond your true budget.
Before signing, pause and ask yourself one powerful question: “If the balloon were due tomorrow, could I realistically pay it without panic?” If the answer is no, think carefully about whether this is truly the right deal for your next car.
The goal is not just to drive away today, but to protect your future self from unnecessary financial pressure. Choose the option that gives you both mobility and peace of mind.