Building Wealth in Your 20s, 30s, and 40s: Age-Adjusted Investing Strategies
Your money decisions in your 20s, 30s, and 40s build the foundation for the rest of your life. Each decade brings different responsibilities, risks, and opportunities, so your investing approach must adapt. There is no single perfect strategy, but there are clear principles and patterns that can guide you.
This article walks through practical, age-adjusted investing strategies for each decade, so you can build wealth steadily, avoid common traps, and feel more in control of your financial future.
Core Principles That Never Change
Before diving into each decade, there are a few timeless rules that apply to everyone, at every age.
First, pay yourself consistently. Investing tiny amounts over long periods beats waiting for the “perfect moment.” Automation removes willpower from the process and makes wealth-building a routine, not a struggle.
Second, spend less than you earn. No investment strategy can outrun chronic overspending. A modest lifestyle with a strong savings habit beats a flashy lifestyle with constant debt.
Third, avoid high-interest debt. Credit card debt and high-rate personal loans quietly destroy wealth. Investing while carrying heavy, expensive debt is like bailing water while your boat is still leaking.
Fourth, understand risk and time. The longer your time horizon, the more risk you can generally take. As you get closer to needing your money, your portfolio should steadily become more conservative.
Your 20s: Build Habits and Take Advantage of Time
Your 20s are the most powerful decade for building wealth—not because you earn the most, but because you have the most time. Time allows compound growth to work quietly in the background.
In this stage, your goals are to:
- Build a strong financial foundation
- Develop automatic saving and investing habits
- Learn the basics of how investing works
Start with a simple safety net. Aim for an emergency fund of 3–6 months of essential expenses. This keeps you from raiding your investments or turning to debt when life happens: job loss, medical bills, car repairs.
Next, attack high-interest debt. If you carry credit card balances, prioritize paying them off. Every extra dollar to high-interest debt is often a better “return” than the stock market can reliably provide.
Once you have a modest emergency fund and a plan for debt, begin investing—even if it feels tiny. For example:
- Start with a low-cost index fund or target-date fund
- Automate monthly contributions, even $50–$100
- Gradually increase the amount with every raise
In your 20s, you can usually afford to be more aggressive with your portfolio, because you have decades to recover from market downturns. A common guideline is a high percentage in stocks and a small percentage in bonds or cash. The exact mix depends on your risk comfort, but your mindset should be growth-oriented.
Use this decade to learn: understand what a stock is, what a bond is, how index funds work, and the power of compounding. You do not need to become a market expert, but you should feel comfortable with long-term, boring investing rather than chasing quick wins.
Your 30s: Balance Growth with Growing Responsibilities
Your 30s often bring major life changes: career advancement, marriage, children, a home purchase, or starting a business. Your investing strategy now has to balance long-term growth with increased responsibilities.
First, revisit your emergency fund. With more obligations, you may want 4–9 months of essential expenses set aside. If children or a mortgage enter the picture, a larger buffer brings peace of mind.
Next, make sure you are maximizing easy opportunities to grow wealth:
- Contribute enough to get full employer retirement matches
- Increase contributions whenever you get a promotion
- Consider tax-advantaged accounts for specific goals
At this stage, it can help to look at your overall financial picture more systematically. Here is a simple illustration of how someone in their 20s, 30s, and 40s might gradually shift their allocation:
| Age Range | Stocks | Bonds | Cash / Short-Term |
|---|---|---|---|
| 20s (early accumulation) | 80–100% | 0–15% | 0–5% |
| 30s (growing responsibilities) | 65–85% | 10–25% | 5–10% |
| 40s (pre-retirement focus) | 50–70% | 20–40% | 10–15% |
These ranges are not rules, but they illustrate how your portfolio can shift gradually from aggressive growth to a more balanced mix. In your 30s, you are usually still focused on growing your money, but you also want protection from big swings that could derail near-term goals.
Many people in their 30s also face a new question: invest or pay down the mortgage faster? The answer depends on your interest rate, risk tolerance, and goals. If your mortgage rate is low, continuing to invest aggressively while making regular payments can make sense. If a faster payoff brings strong emotional relief, directing extra money there can still be a wise choice.
Your 30s are also a powerful decade to protect your earning power. Consider:
- Building skills that increase your income over time
- Exploring side income opportunities that align with your strengths
- Securing appropriate insurance to protect your family
Remember, increasing your income while maintaining or only modestly increasing your lifestyle can turbocharge your investing. That growing gap between income and spending is where real long-term wealth is created.
Your 40s: Protect, Fine-Tune, and Accelerate
By your 40s, the future no longer feels abstract. Retirement, college for children, or dreams like relocating or changing careers move from “someday” to specific timelines. Your investing strategy should protect what you have built and deliberately aim at those targets.
First, clarify your major goals. For example:
Do you want to retire at 60 or work into your late 60s? Are you planning to pay fully for your children’s education, or partially? Do you envision downsizing your home, or staying put?
With clearer goals, you can fine-tune your investing plan. In your 40s, shifting to a more balanced portfolio can reduce the chance that a severe market downturn near your 50s or early 60s forces unpleasant choices.
Regularly review and rebalance your portfolio. Over time, market movements can push your allocations out of line. Once or twice a year, check your percentages and adjust them back to your intended mix. This helps you systematically buy more of what has lagged and trim what has surged, without emotional decision-making.
Consider diversifying beyond only one type of investment. Many people in their 40s benefit from a combination such as:
- Broad stock index funds for growth
- Bond funds or fixed income for stability
- Some exposure to real assets, depending on goals
At this stage, it is also wise to stress-test your plan. Ask yourself: If the market dropped significantly and stayed down for several years, would I still be on track? If the answer is no, you may be taking on more risk than you realize.
Your 40s can also be a powerful decade for catch-up. If your 20s or 30s were financially challenging, you can still build meaningful wealth now by:
Increasing your savings rate aggressively, channeling bonuses or windfalls into investments, and keeping lifestyle inflation under control even as your income grows.
It is easy to look back and wish you had started earlier. Instead, focus on the leverage you have now: likely higher income, more clarity about your goals, and the experience to make steady, thoughtful decisions.
Adapting at Any Age and Starting Where You Are
No one’s life follows a perfect script. Some people in their 20s support family members. Some in their 30s go back to school. Some in their 40s restart after divorce, illness, or job loss. You are not behind—you are simply starting from today.
Regardless of your age, you can:
Understand your current situation clearly, choose a simple investment approach appropriate for your time horizon, and automate consistent contributions. Then, review your plan once or twice a year instead of reacting to every headline.
Wealth is not built by one lucky decision. It is built by hundreds of small, boring choices made over many years: spending slightly less, saving slightly more, learning a little each year, staying invested through ups and downs.
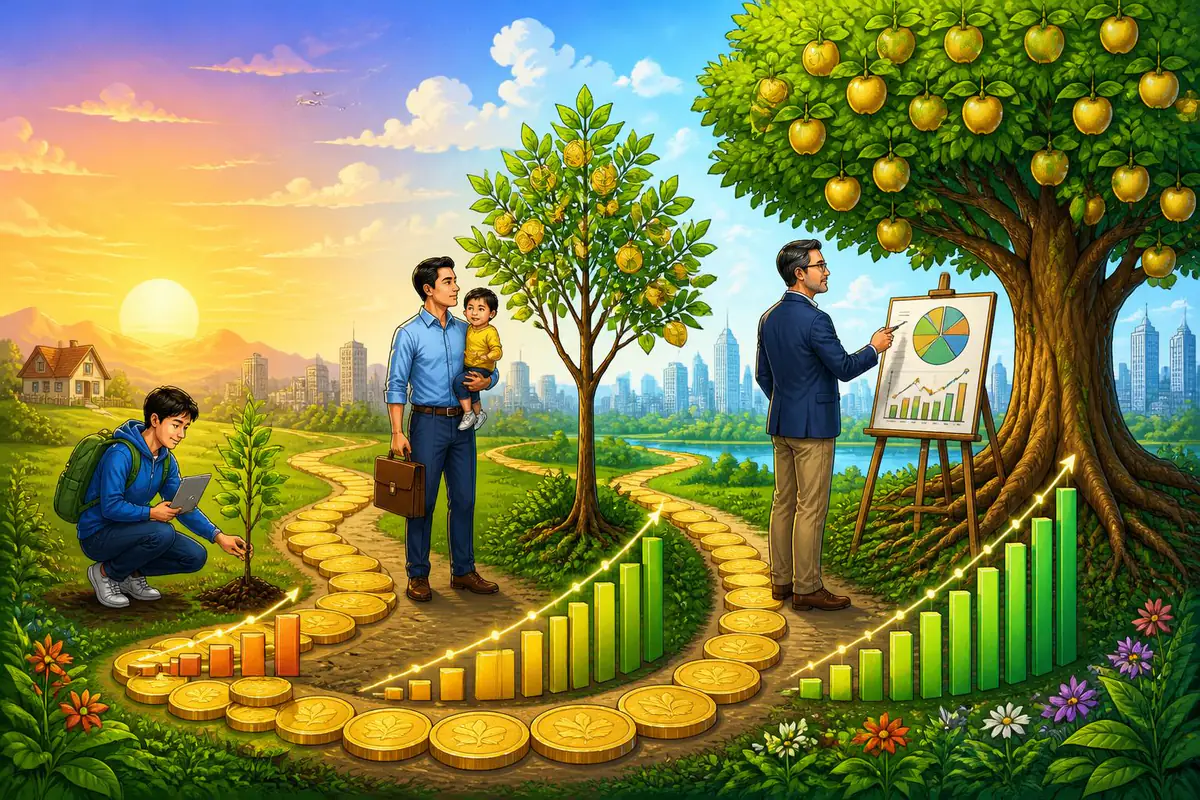
Your 20s give you time, your 30s give you momentum, and your 40s give you focus. Use each decade for what it offers, and let your investing strategy evolve with you.
The best moment to start was in the past. The second-best moment is the one you control: right now.