Dealer Financing vs. Bank Loans: Who Really Offers the Better Deal?
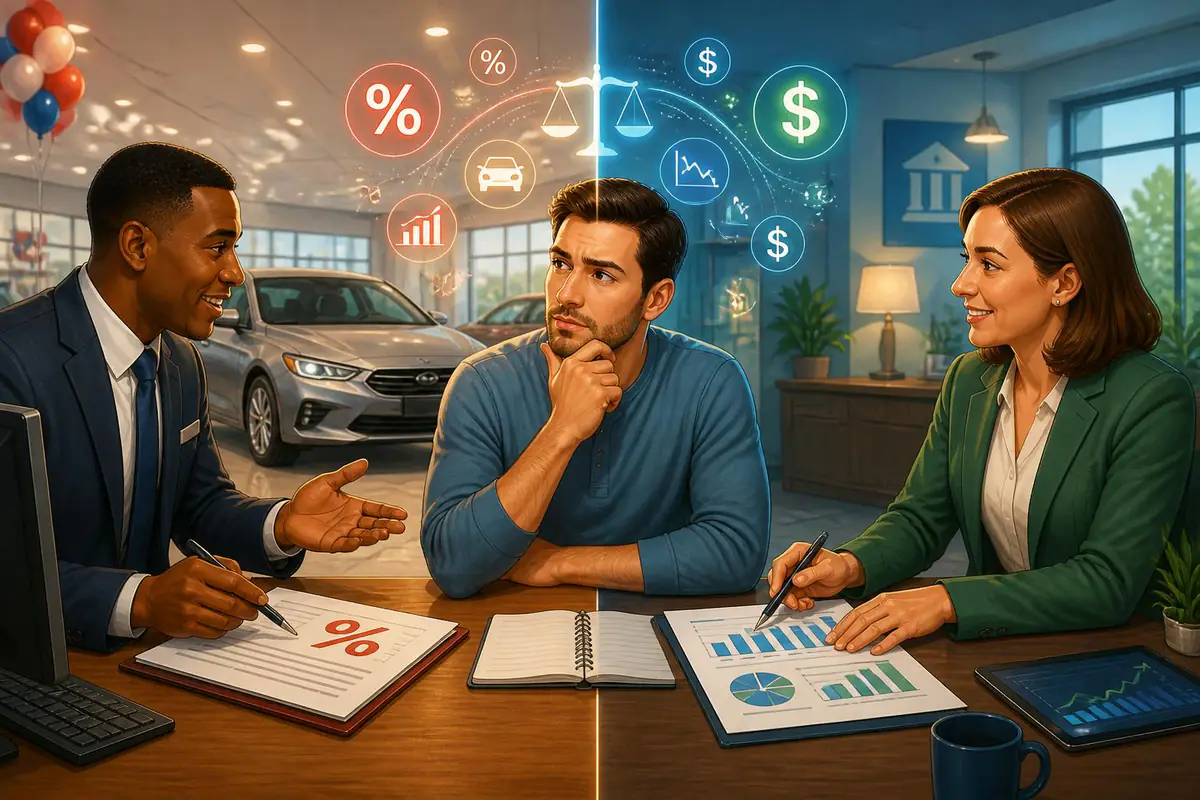
When it’s time to buy a car, one of the first big questions is simple yet stressful: should you finance through the dealership or go to a bank or credit union? Both options can put you behind the wheel, but they do it in very different ways.
Understanding those differences can save you thousands of dollars, months of stress, and even protect your long-term financial health. Instead of guessing, you can learn how each option really works and which one fits your situation best.
How Dealer Financing Works in Practice
Dealer financing is often called “in-house” or indirect financing. You choose your car at the dealership, sit with the finance manager, and they arrange the loan on your behalf.
Behind the scenes, most dealers are not actually lending you the money. They submit your application to one or more lenders—banks, captive finance companies (like Ford Credit or Toyota Financial), or other finance institutions—and then present you with an offer.
Here’s what typically happens with dealer financing:
- You pick a car and agree on the purchase price.
- You fill out a credit application at the dealership.
- The dealer shops your application to partner lenders.
- The lender returns an approval with an interest rate and terms.
- The dealer may add a markup to that rate before showing it to you.
This markup is legal in many places and is one way dealers make money. That means the rate you see might be higher than the rate the lender originally offered behind closed doors.
On the positive side, dealer financing can be very convenient. You handle the car selection and loan in one place, often on the same day, which is helpful if you need a vehicle quickly.
How Bank and Credit Union Loans Work
Bank or credit union loans are usually called direct auto financing from a lender. You go to the bank or credit union yourself—online or in person—before or after visiting the dealership, and you apply for an auto loan in your own name.
With this route, you control more of the process:
- You compare rates and terms from multiple lenders.
- You get pre-approval for a specific amount and rate.
- You take that approval to the dealer as a “cash buyer.”
Being a pre-approved buyer changes the dynamic. Instead of focusing on monthly payments, you can negotiate based on the total out-the-door price, which often leads to better deals.
Credit unions, in particular, are known for offering competitive rates, especially to members with solid credit. They may also be more flexible with people who have limited or imperfect credit histories.
Interest Rates, Terms, and Total Cost: The Real Comparison
To decide who offers the better deal, you need to compare more than just the monthly payment. The key factors are:
- Interest rate (APR) – what you pay to borrow the money
- Loan term length – how many months you’ll be paying
- Total amount financed – price plus taxes, fees, extras
Dealers sometimes advertise very low or even 0% financing for new cars. These offers can be excellent, but they often come with conditions: top-tier credit, limited models, or giving up cash rebates that might save you more money upfront.
Meanwhile, banks and credit unions might offer slightly higher rates on paper but better flexibility. You may be able to shorten your loan term, make extra payments without penalty, and avoid add-ons that quietly increase the total cost.
| Aspect | Dealer Financing | Bank / Credit Union Loan |
|---|---|---|
| Convenience | One-stop shop at dealership | Separate step before or after shopping |
| Rate Transparency | Rate can include dealer markup | Rate set directly by lender |
| Promotions | 0% or special incentives possible | Fewer promotions, steadier pricing |
| Negotiating Power | Focus may shift to payment size | Lets you negotiate as cash buyer |
| Flexibility | Terms tied to partner lenders | Likely more options, especially at credit unions |
The Psychological Trap of “Monthly Payment Thinking”
One of the most powerful tools in a dealer’s toolbox is focusing on the monthly payment instead of the total price. It sounds harmless: you say what you can afford per month, and they “work the numbers” to fit it.
But this can hide several costly moves:
They might stretch the loan from 60 to 72 or 84 months to lower your monthly payment. On paper, your budget looks happy. In reality, you could be paying thousands more in interest over the life of the loan and staying in debt far longer.
Always flip the conversation. Instead of asking, “What’s the monthly payment?”, ask:
“What’s the out-the-door price?” and “What’s the APR and total interest over the life of the loan?” Those questions keep the numbers honest.
When Dealer Financing Can Be the Better Deal
Dealer financing is not automatically bad. In some situations, it can be your best option.
Dealer financing may be better when:
- There is a genuine 0% or ultra-low APR offer you qualify for.
- The dealer offers large rebates only with their financing.
- You have weaker credit and the dealer’s network finds approval where your bank cannot.
Even then, run the math. Sometimes taking a rebate plus a slightly higher bank rate is cheaper than taking a low dealer rate without the rebate.
If you choose dealer financing, ask directly whether the rate includes any dealer markup, and request to see all fees and add-ons in writing before signing.
When Bank or Credit Union Loans Win
A bank or credit union is often the better choice when you value clarity, control, and long-term savings over convenience.
You might lean toward direct financing if:
You want to compare multiple offers objectively. You prefer negotiating the car price separately from financing. You dislike pressure to buy extras like extended warranties or add-on insurance rolled into the loan.
Credit unions are especially strong for people who:
Have good but not perfect credit, want fair and transparent terms, and appreciate a more relationship-based approach to lending. They may explain your options more patiently and help you choose a payment schedule that fits your budget.
How to Protect Yourself and Get the Best Deal
Regardless of which route you choose, a few simple actions can dramatically improve your outcome and reduce stress.
Use these practical steps:
- Know your credit score range before you apply anywhere.
- Get pre-approved with a bank or credit union so you have a benchmark.
- Negotiate the car price first, then discuss financing.
- Compare the dealer’s offer to your pre-approval based on total cost, not just payment.
- Read every line before signing, and do not rush the process.
If the dealer’s financing clearly beats your pre-approval—lower APR, similar term, no hidden fees—it may make sense to accept it. If not, you can confidently stick with your bank or credit union.
Empowering Yourself as a Car Buyer
There is no single answer that fits everyone. The “better deal” depends on your credit profile, the specific promotions available, and how disciplined you are during negotiations.
What matters most is that you approach the process with information and intention. You don’t have to accept the first offer placed in front of you. You can pause, compare, ask questions, and even walk away.
When you focus on total cost, clear terms, and your long-term financial health, you put yourself back in control. Instead of wondering whether the dealer or bank “won,” you can drive away knowing you made a smart, informed choice—for your budget today and your goals tomorrow.