First-Time Buyer’s Guide to Vehicle Financing Without Getting Burned
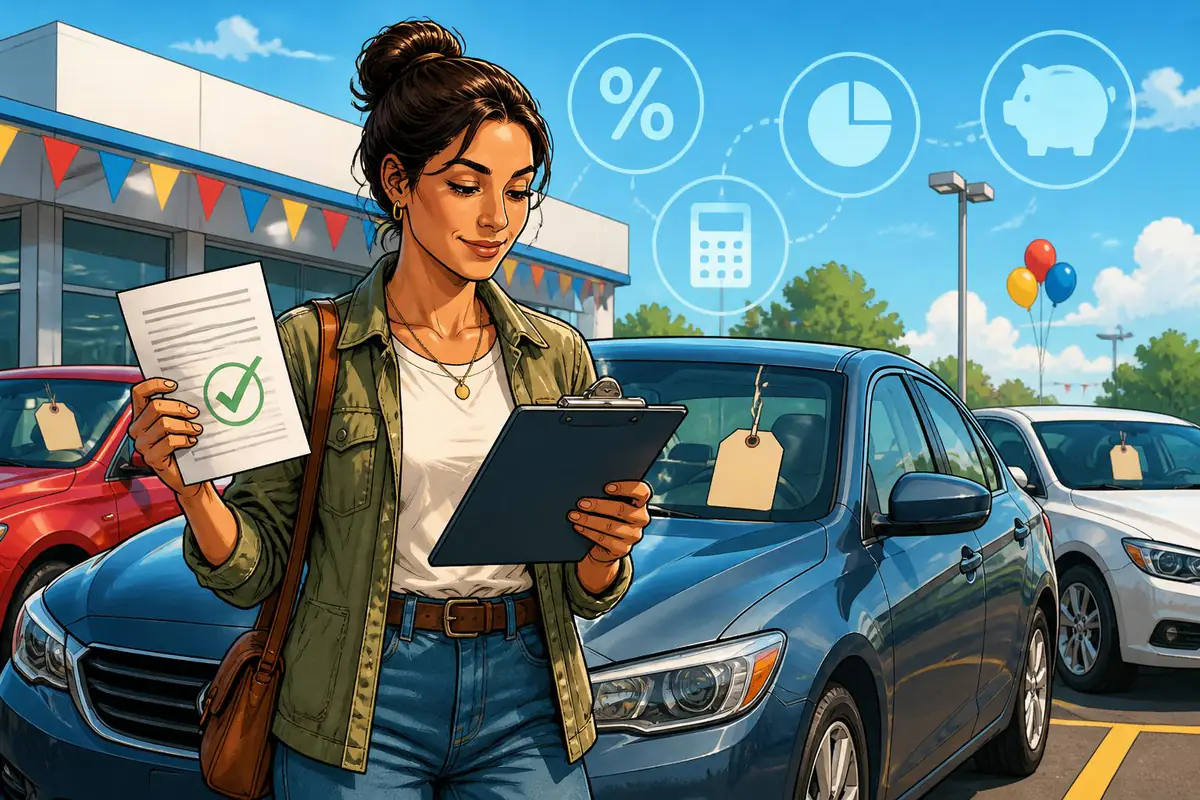
Buying your first car is exciting, but the financing part can feel intimidating. Contracts, interest rates, dealer offers, credit scores – it’s a lot. Without the right knowledge, it’s easy to overpay or lock yourself into a bad deal that hurts your finances for years.
This guide walks you through vehicle financing step by step so you can choose confidently, protect your wallet, and avoid common traps that catch many first-time buyers.
Step 1: Get Clear on Your Real Budget
Most first-time buyers start by asking, “What monthly payment can I afford?” That’s a useful question, but dealers can manipulate payments by stretching out loan terms. You might think you’re getting a good deal when you’re actually paying far more in interest over time.
Instead, begin with your total financial picture. Look at your monthly net income and list your regular expenses: rent, food, insurance, subscriptions, savings, and debts. What’s left is your pool for transportation costs, not just the car payment.
Include these in your monthly car budget:
- Loan payment plus interest (principal and finance charges)
- Full-coverage insurance premium (often required by lenders)
- Fuel or charging costs
- Maintenance and repairs
- Registration, taxes, and inspection fees
A common rule of thumb is to keep all car-related costs under 15–20% of your take-home pay. If that number feels tight, it’s a sign to consider a lower-priced vehicle, a larger down payment, or waiting a bit longer.
Step 2: Know Your Credit Score Before You Shop
Your credit score is one of the biggest factors in determining your interest rate. Dealers and lenders will definitely look at it, so you should too—before you start talking about cars.
Check your credit score and your credit reports from major bureaus. If you find mistakes, dispute them. Even a small bump in your score can save you thousands of dollars over the life of a loan.
If your score is low or thin because you’re just starting out, consider:
- Paying down existing credit card balances
- Making all payments on time for several months
- Becoming an authorized user on a responsible person’s card
- Building history with a small, manageable credit product
Taking even three to six months to improve your score can turn a painful loan into a manageable one.
Step 3: Get Pre-Approved Before Visiting a Dealer
One of the best protections against getting burned is to secure a loan pre-approval from a bank, credit union, or reputable online lender before you step onto a car lot.
Pre-approval gives you:
A clear interest rate range and loan amount based on your actual credit profile, not a guess. It also turns you into a “cash buyer” at the dealership, which changes the conversation from monthly payment games to total price.
When comparing pre-approvals, look at:
| Factor | What to Check |
|---|---|
| APR (Annual Percentage Rate) | Includes interest and many fees; best measure of total cost. |
| Loan Term Length | Shorter terms usually mean higher payments but lower total interest. |
| Prepayment Penalties | Fees if you pay off the loan early—ideally, there should be none. |
| Down Payment Requirements | Minimum amount you must put down to qualify. |
Walk into the dealership knowing your maximum approved rate and amount. If the dealer offers worse terms, you already have a backup.
Step 4: Separate the Car Price from the Financing
A common mistake is letting the dealer control every part of the conversation: vehicle price, trade-in value, and financing all mixed together. This makes it easy for them to give you a good number in one area while quietly taking it back in another.
Protect yourself by negotiating in this order:
- Agree on the vehicle price first, before discussing monthly payments or financing.
- Then talk about your trade-in value, if you have one.
- Only after that, discuss financing options.
Keep telling the salesperson, “Let’s settle the price of the car first” if they try to pull you into monthly payment discussions. The shorter and clearer the negotiation, the less room there is for hidden markups.
Step 5: Choose the Right Loan Term and Down Payment
Longer terms (72 or 84 months) may look attractive because they lower your payment, but they can lead to paying far more interest and staying in debt for most of the car’s useful life.
Whenever possible:
- Aim for a term of 36–60 months
- Put at least 10–20% down, especially for a new car
- Choose the shortest term with a payment you can comfortably handle
A solid down payment helps you avoid being “upside down” (owing more on the loan than the car is worth), which becomes a major problem if you need to sell the car or if it’s totaled in an accident.
Step 6: Watch Out for Add-Ons and Hidden Costs
After you’ve agreed on a price, you’ll likely be moved to the finance office. This is where many first-time buyers get burned. You’ll be offered extended warranties, paint protection, wheel and tire coverage, service contracts, gap insurance, and more.
Some of these can be useful, but many are overpriced or unnecessary. Others are quietly rolled into the loan, increasing what you pay interest on. Ask for the cost of every add-on and how it affects your monthly payment and the total loan amount.
Guidelines to protect yourself:
Only consider add-ons you clearly understand and genuinely need. Decline anything you feel pressured to buy on the spot. You can often purchase similar coverage later from third parties at lower prices.
Above all, read the itemized breakdown carefully. Look out for “doc fees” and dealer extras that don’t seem reasonable. You’re allowed to question and negotiate them, or walk away if the numbers don’t make sense.
Step 7: Understand Every Line of the Contract
Never sign anything you don’t fully understand. Take your time with the contract, even if the salesperson seems rushed.
Key items to verify on the final loan paperwork:
The exact purchase price of the vehicle matches what you agreed. The APR and loan term are the same as discussed. There are no surprise products or fees added that you didn’t authorize.
If anything is unclear, ask questions and get clear explanations. You’re making a multi-year commitment. A good dealer will respect your need to review carefully. If they don’t, consider that a red flag.
Step 8: Plan for Life After the Purchase
Once you drive off the lot, the real test begins: can you comfortably handle this payment and still move toward your other financial goals?
Set up automatic payments to avoid late fees and protect your credit. If you get a raise or reduce other expenses, consider paying a little extra each month toward the principal (as long as your loan has no prepayment penalties).
Also, keep an eye on interest rates and your improving credit profile. If rates drop or your credit score significantly increases, you might be able to refinance to a better rate and lower total cost.
Red Flags That Mean You Should Walk Away
No matter how much you like a car, there are situations where the smartest move is to leave and rethink. Watch for:
- Pressure to sign “today only” deals you can’t verify
- Refusal to show you the full breakdown of costs
- Major differences between what you discussed and what’s on paper
- Dealers refusing to honor your outside pre-approval
- Feeling rushed, overwhelmed, or confused instead of informed
Walking away can be uncomfortable in the moment, but it’s far better than staying stuck in a bad car loan for years.
Turning Your First Loan into a Smart Move
Your first vehicle loan isn’t just about transportation. It’s also a powerful chance to build credit, learn how major financing works, and prove to yourself that you can handle big financial decisions wisely.
When you take the time to understand your budget, know your credit, secure pre-approval, separate negotiations, and read everything you sign, you dramatically reduce the risk of being taken advantage of.
Instead of getting burned, you drive away with a car you can afford, a contract you understand, and the confidence that you made a smart, informed choice. That’s the best way to start your journey as a vehicle owner—and to set yourself up for even better deals in the future.