How to Spot Predatory Lenders and Avoid Loan Scams
Borrowing money can be stressful, especially when you urgently need cash. That stress is exactly what predatory lenders and loan scammers exploit. They promise fast approval, no credit checks, and guaranteed acceptance—but often hide traps that leave you deeper in debt or even steal your identity.
Understanding how these scams work is your best defense. When you know the warning signs, you can protect yourself, your family, and your future.
What Is a Predatory Lender?
A predatory lender is any individual or company that uses unfair, deceptive, or abusive tactics to get you to take a loan that harms you. These lenders usually target people who are financially vulnerable, have poor credit, or feel desperate.
Predatory loans are often legal on paper but structured to trap you in a cycle of debt. Loan scams, on the other hand, are outright frauds designed to take your money or personal information without providing a legitimate loan.
Common Types of Predatory Loans and Scams
Knowing the different forms these schemes take makes them easier to recognize and avoid.
- Payday loans: Very short-term loans with extremely high fees and interest rates, often due on your next payday.
- Title loans: Loans using your car title as collateral; if you miss payments, you can lose your vehicle.
- Advance-fee loan scams: Fake lenders who ask for money upfront and then disappear without providing a loan.
- Loan flipping: Encouraging you to refinance repeatedly, adding new fees and extending your debt.
- Online impersonation: Scammers pretending to be banks, government agencies, or well-known companies to gain your trust.
Not every short-term or high-interest loan is a scam, but when several red flags appear together, it’s a strong signal to walk away.
Key Red Flags of Predatory Lenders
Crooked lenders tend to use the same tricks. Watch for these warning signs whenever you consider borrowing money.
1. Pressure to Act Immediately
Predatory lenders want you to rush instead of think. They use urgency to keep you from reading details or comparing offers. You may hear phrases like:
- “Offer expires tonight.”
- “You must pay the fee within an hour.”
- “Don’t worry about the paperwork, just trust me.”
A trustworthy lender will give you time to read the agreement and ask questions. If someone pressures you to sign immediately, consider it a major warning sign.
2. Guaranteed Approval, No Matter What
Legitimate lenders assess risk. They may check your credit, your income, or your employment. Scammers, however, often advertise “100% guaranteed approval loans” or “no credit check, ever.”
If a lender doesn’t seem to care whether you can repay, it means they make money even when you fail—usually through fees, penalties, or seizing collateral like your car or home.
3. Upfront Fees Before You Get the Money
One of the clearest signs of a loan scam is being asked to pay money before receiving the loan. Scammers may call these charges:
- Processing or administrative fees
- Insurance or guarantee fees
- Registration or verification costs
Legitimate lenders typically subtract any approved fees from the loan amount or clearly disclose them in the contract. They do not demand that you send cash, gift cards, cryptocurrency, or money transfers upfront in order to “release” a loan.
4. Vague or Hidden Costs
Another classic tactic is confusion. Predatory lenders may avoid giving you clear numbers, change the subject when you ask about costs, or hide crucial details in fine print.
You should always know the:
| Key Loan Term | What You Should Know |
|---|---|
| Interest rate (APR) | The true yearly cost of borrowing, including fees. |
| Monthly payment | How much you will owe each month, and for how long. |
| Total repayment | The total amount you will pay back over the life of the loan. |
| Late fees and penalties | What happens if you miss or delay a payment. |
If a lender refuses to give this information in writing, step away.
5. Requests for Unusual Payment Methods
Scammers love methods that are hard to trace or reverse. Be extremely cautious if a lender insists you pay with:
Gift cards, wire transfers, cryptocurrency, or payment apps to a personal account. A serious, regulated lender will use standard banking channels and clear, professional billing methods.
6. Suspicious Communication and Unprofessional Behavior
Many scams start with unsolicited calls, texts, emails, or social media messages. You might receive messages claiming you are “pre-approved” for a loan you never requested. Other warning signs include:
Refusal to meet in person, no physical address, poorly written contracts, or aggressive and rude customer service. Professional lenders respect your questions and provide clear contact information.
How to Check If a Lender Is Legitimate
Instead of relying on gut feeling alone, use practical checks to confirm whether a lender is trustworthy.
First, verify registration or licensing with the relevant authority in your region. Legitimate lenders usually must be registered or licensed to operate.
Next, search the company name plus words like “complaint,” “scam,” or “reviews.” A pattern of unresolved complaints, stories of unexpected charges and harassment, or warnings from consumer agencies is a strong signal to avoid them.
Finally, check whether the lender clearly displays terms, interest rates, and company information on official materials. If you only find a social media page or messaging account, proceed very carefully or not at all.
Practical Steps to Protect Yourself Before Borrowing
Even when you are under financial pressure, taking a few protective steps can save you from years of debt and stress.
- Compare multiple offers: Do not accept the first loan you see. Even a small difference in interest can save you a lot over time.
- Calculate total repayment: Use a calculator or simple math to understand how much you will pay in total, not just the monthly amount.
- Read every line: Go through the contract slowly. Look for mentions of variable rates, extra fees, add-on products, or automatic renewals.
- Ask someone you trust: A friend, family member, or advisor can provide a calmer perspective, especially if you feel pressured.
Taking these steps shifts you from a rushed, emotional decision to a deliberate and informed one.
Safer Alternatives When You Need Money
Predatory lenders thrive when people feel they have no other options. Exploring even imperfect alternatives can be far better than entering a harmful loan.
You might consider:
Negotiating payment plans with existing creditors, asking your employer about salary advances, or checking whether there are community organizations that offer low-cost emergency assistance. Some regions have credit unions or nonprofit lenders with more flexible terms.
If you already have debt, speaking with a reputable credit counselor or financial advisor can help you prioritize payments and reduce pressure without taking dangerous new loans.
What to Do If You Suspect a Scam
If something feels wrong, trust that feeling and pause. You can:
Stop all communication, avoid sending any documents or money, and collect evidence such as emails, screenshots, loan offers, and messages. Then report the incident to local consumer protection authorities or fraud hotlines in your area.
If you already shared personal information like ID numbers or bank details, contact your bank immediately. Ask about freezing or monitoring your accounts, and watch your statements carefully for unauthorized activity.
Building Confidence as an Informed Borrower
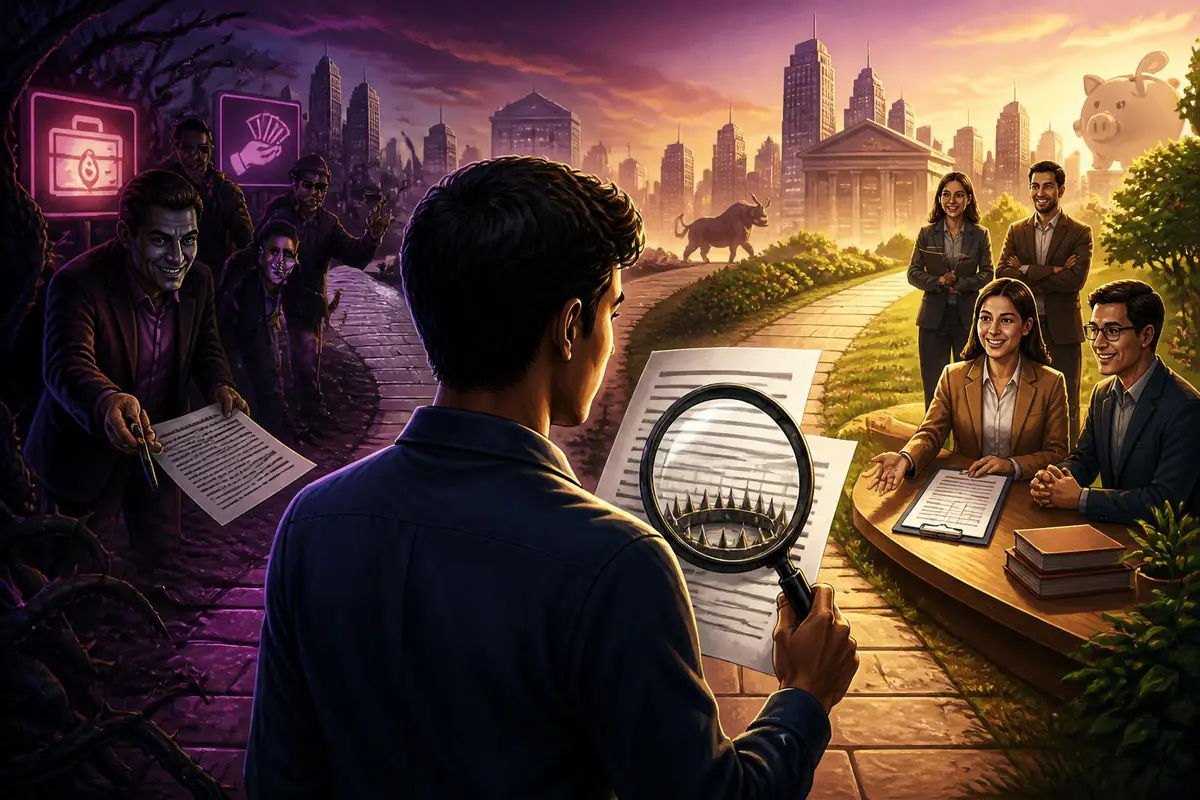
Predatory lenders rely on confusion, fear, and urgency. The more informed you are, the less power they have over you. When you understand your rights, common tricks, and safer options, you become a much harder target.
Before signing any loan, pause and ask yourself:
Do I fully understand the cost? Can I realistically make these payments? Is this lender open, transparent, and licensed? If the answer to any of these is no, you have the power to walk away and look for better, safer solutions.
Protecting yourself from loan scams is not just about saying “no” to bad offers; it is about saying “yes” to clear information, fair treatment, and dignity in your financial life. You deserve that, no matter your credit score or income level.