Leasing vs. Financing: Which Vehicle Option Truly Saves You Money?
Choosing between leasing and financing a vehicle is one of those decisions that can quietly shape your finances for years. The monthly payment may look manageable today, but the long-term impact on your cash flow, debt load, and future options can be huge.
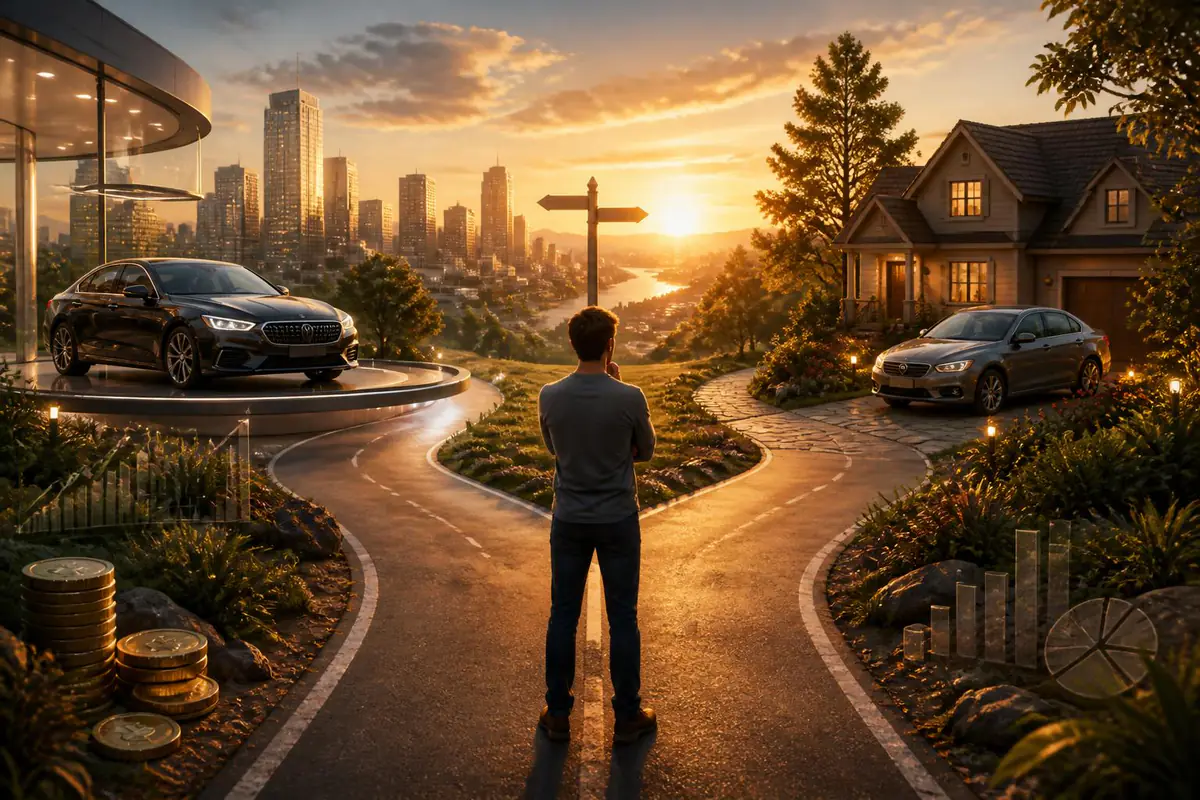
Instead of asking only, “What’s the lowest monthly payment?”, a better question is: “Which option truly builds my wealth?” To answer that, you need to look beyond dealership pitches and understand how each path really works.
How Leasing Works: Paying for Use, Not Ownership
When you lease, you’re essentially paying for the depreciation of the car during the lease term, plus interest (often called the money factor) and fees. At the end, you return the car—or buy it for a preset residual value.
A typical lease includes:
- A small or moderate down payment (sometimes zero down).
- Monthly payments for 24–48 months.
- Mileage limits, such as 10,000–15,000 miles per year.
- Charges for excess mileage and excessive wear and tear.
Because you’re not paying off the entire vehicle price, monthly lease payments are usually lower than loan payments on the same car. That’s the main attraction for many drivers.
However, once the lease ends, you typically have no asset. You give the car back and, if you want another one, you start a new payment cycle. That’s why leasing can feel like “forever renting your car”.
How Financing Works: Building Ownership Over Time
Financing means taking out a loan to buy the car. You either own it outright (if you pay cash) or the lender holds the title until you’ve made all your payments.
With financing, your monthly payment covers:
- The principal (the actual price of the car, minus any down payment).
- Interest charged by the lender.
- Sometimes add-ons like extended warranties or fees rolled into the loan.
At the end of the loan term—commonly 36 to 72 months—the payments stop, but you still have a vehicle you can continue to use, sell, or trade. This is the key benefit: you’re building equity in an asset, even though that asset depreciates.
Financing payments are usually higher than lease payments on the same car, but a well-chosen financed vehicle can give you several years of payment-free driving once the loan is repaid.
The Real Cost: Comparing Leasing and Financing Over Time
To see which option really saves you money, you need to look at the total cost over a realistic timeframe, not just the monthly bill. Consider at least a 6–10 year horizon, because that’s where financing often pulls ahead.
Imagine two drivers choosing the same car:
| Aspect | Leasing (3-year cycles) | Financing (5-year loan) |
|---|---|---|
| Initial monthly payment | Lower | Higher |
| Ownership at the end | No ownership unless buyout | You own the car |
| Payments after year 5 | Likely still paying on new lease | Potentially no payments |
| Mileage flexibility | Restricted by contract | Unlimited (within reason) |
| Wear-and-tear penalties | Possible at turn-in | No formal penalties |
If you’re the kind of person who keeps a car for 8–10 years, financing often wins financially because you spread the purchase cost over more years of use. Your “cost per year” and “cost per mile” drop significantly once the loan is paid off.
On the other hand, if you value driving a new car every three years and are comfortable with continuous payments, leasing may feel smoother and more predictable, though usually at a higher lifetime cost.
Key Money-Saving Questions to Ask Yourself
Instead of focusing on what the dealer wants to sell you, start by asking yourself a few honest questions. These will often reveal whether leasing or financing better fits your life—and your wallet.
Ask yourself:
- How many miles do I really drive each year? If you exceed 12,000–15,000 miles regularly, leases can punish you with per-mile penalties.
- Do I usually keep cars for a long time, or do I want something new every few years?
- How stable is my income? Could I handle a slightly higher payment now for future years without payments?
- Am I disciplined enough to invest the difference if I choose the cheaper monthly option?
Those questions matter more than any promotion or discount, because they reflect your real behavior, not just your intentions.
Hidden Costs That Quietly Change the Math
Both leasing and financing come with extra charges that can shift which option is truly cheaper. Ignoring them is a common—and costly—mistake.
With leasing, watch for:
Excess mileage fees, which can be surprisingly high if you underestimate your driving. Also consider wear-and-tear charges for things like dents, scratches, or worn interiors. Finally, there may be disposition fees at lease end, a charge just for returning the vehicle.
With financing, look closely at:
Interest rate and loan length—stretching a loan to 72 or 84 months can make payments look affordable but increase total interest dramatically. Also consider that out-of-warranty repairs become your responsibility once manufacturer coverage ends, especially if you keep the car for many years.
The more accurately you account for these costs, the clearer the smarter choice becomes.
When Leasing Can Make Financial Sense
Leasing is not always a bad financial move. In certain situations, it can be reasonable—or even smart—if you use it intentionally.
Leasing may work well if:
- You consistently drive fewer miles than the standard lease limit, and you’re confident about it.
- You prioritize always having a new, reliable car with the latest safety features and don’t want to worry about aging-vehicle repairs.
- You can write off leasing costs through a business or self-employment, under proper tax guidance.
- You negotiate strongly and understand the residual value, money factor, and fees, not just monthly payments.
Even then, leasing is usually about convenience and lifestyle more than squeezing every last dollar of value. That’s fine, as long as you’re honest with yourself about the trade-off.
When Financing Usually Saves You More
Financing often leads to better long-term savings when you approach it strategically. The real power of financing is unlocked when you avoid constant trading and instead keep a solid car well after the loan is paid.
Financing shines when:
You’re willing to drive a car for 7–10 years, keep it maintained, and accept that it won’t always feel brand-new. You choose a vehicle known for reliability and reasonable depreciation, rather than chasing the latest trends. You also avoid rolling negative equity from one loan into the next, which can trap you in perpetual car debt.
Once the loan ends, you can redirect what used to be a car payment into emergency savings or investments. Over several years, that habit can be worth tens of thousands of dollars.
Practical Steps to Decide What’s Best for You
To move from theory to a practical decision, follow a simple process before you sign anything at the dealership.
First, determine your real budget: decide what you can comfortably afford each month without stretching, considering insurance, fuel, and maintenance as part of your transportation cost.
Second, get actual numbers: request a detailed breakdown for both a lease and a purchase of the same car—total price, down payment, monthly payment, interest rate or money factor, and all fees.
Third, compare total cost over time: for leasing, assume you’ll lease again when the term ends; for financing, assume you’ll keep the car at least several years after payoff. Estimate what your finances look like after six to ten years under each path.
Finally, align with your values: if financial freedom is a high priority, favor the option that leads to fewer years with payments and more years owning your car outright. If driving a new car regularly matters more and you can afford it responsibly, a well-structured lease might fit.
The Bottom Line: Saving Money Means Playing the Long Game
Leasing versus financing is not just a question of monthly payment size; it’s a decision about how you handle debt, ownership, and long-term stability.
If your goal is to truly save money and build financial strength, financing a reliable car—and keeping it for many years after payoff—is usually the winner. Leasing can make sense in specific scenarios, but it tends to keep you in a cycle of permanent payments.
The most important step is to choose with intention. Run the numbers, be honest about your habits, and commit to the path that gives you more control over your money in the long run. Your future self, driving a paid-off car with money in the bank, will be grateful you did.