Long-Term Car Loans: Lower Monthly Payments, Higher Lifetime Costs
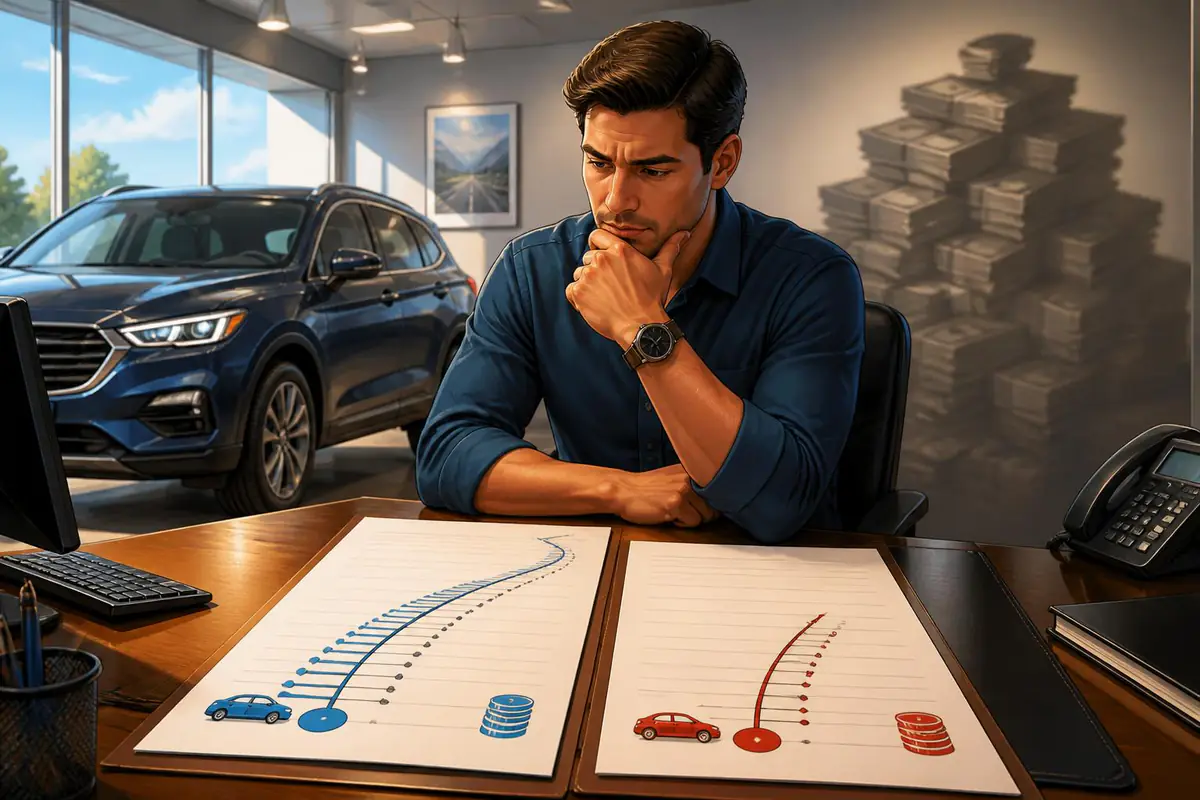
Many buyers walk into a dealership focused on just one thing: the monthly payment. When the salesperson stretches the loan from 60 to 72 or even 84 months, that number magically shrinks. The car suddenly feels “affordable.”
But what feels affordable today can quietly become far more expensive over time. Long-term car loans reduce your monthly payment, yet they usually increase how much you pay overall. Understanding how and why this happens is essential to protecting your long-term financial health.
How Long-Term Car Loans Work
A long-term car loan is typically any auto loan longer than 60 months, often running 72, 84, or even 96 months. The structure is simple: you borrow a set amount, pay interest on it, and repay it over many years.
Because the loan is stretched out, the monthly payment drops. That’s why dealers often say, “We can make this fit your budget.” But the trade-off is that you pay interest for a longer period, and even a fairly low rate can turn into a huge total interest cost when multiplied over many years.
The danger is subtle. You do not feel it in any single month. You feel it in the long run, when you realize how much of your money went to interest instead of savings, investments, or more important goals.
Why Lower Monthly Payments Can Be Misleading
Our brains love smaller numbers. A payment of $450 per month feels safer than $650, even if the higher payment actually saves you thousands of dollars overall. This is a psychological trap.
Lenders and car dealers know this. They highlight the monthly payment because it makes expensive cars appear within reach. But your real question should be: “What is the total cost here?” That includes principal, interest, fees, and how long you will be paying.
When you focus only on the monthly payment, you give up control over the bigger picture. You might end up with a car that strains your finances for years, reducing your flexibility to handle emergencies, invest, or pursue other dreams.
The Hidden Costs of Long-Term Car Loans
The most obvious hidden cost is total interest. On a long-term loan, you may easily pay thousands more than you would on a shorter-term loan for the same car.
But there are other, less obvious dangers that can quietly erode your financial stability.
- More years of paying interest means less money going into savings, retirement, or debt repayment elsewhere.
- Higher risk of negative equity—owing more on the car than it is worth—for a longer period.
- Greater pressure to keep the car even when repairs grow expensive, because you still owe on the loan.
- Reduced flexibility in your budget, making it harder to handle job loss, medical bills, or life changes.
Cars are depreciating assets. They lose value every year, but your loan does not shrink nearly as fast. With a long-term loan, the car’s value and the loan balance rarely move in harmony. This is where negative equity becomes a serious problem.
Understanding Negative Equity: Owing More Than the Car Is Worth
Negative equity happens when your loan balance is higher than the market value of your car. This is especially common early in a long-term loan, when most of your payment goes to interest and the car is depreciating quickly.
Imagine needing to sell your car or trade it in after a couple of years. If you still owe more than it is worth, you must either bring cash to the table or roll the negative balance into a new loan. Rolling it over means you are now paying for part of your old car and your new car at the same time.
This debt stacking can trap you in a cycle of perpetual car payments and stress. You move from one loan to another, never getting ahead, always carrying yesterday’s balance into tomorrow’s obligations.
When a Long-Term Car Loan Might Make Sense
Not every long-term loan is automatically a mistake. In some cases, it can be a reasonable choice—if handled with caution and clarity.
A long-term loan might be acceptable if:
- The interest rate is very low, and you could easily afford a shorter term.
- You plan to keep the car well beyond the life of the loan.
- You have a strong emergency fund and stable income.
- You are using the lower payment to free up money for higher-priority financial goals, such as paying off high-interest debt.
Even then, you should calculate the total interest and consider whether paying extra each month could shorten your term and reduce your lifetime cost.
A Simple Comparison: Short-Term vs. Long-Term Loan
Consider this simplified example for a $30,000 car at 6% interest:
| Loan Term | Approx. Monthly Payment | Approx. Total Interest Paid |
|---|---|---|
| 60 months (5 years) | $580 | $4,800 |
| 84 months (7 years) | $440 | $7,900 |
The 84-month loan saves you about $140 per month, but costs roughly $3,100 more in interest over the life of the loan. The lower payment feels better, yet the long-term hit to your finances is clear.
Now ask yourself: could you find $140 elsewhere in your budget to avoid paying more than $3,000 extra? Often the answer is yes—with some planning and discipline.
Practical Strategies to Reduce Lifetime Car Costs
You do not need to be a finance expert to make smarter car decisions. A few intentional choices can protect you from the worst effects of long-term loans.
Consider these strategies:
- Buy less car than you can afford. A reliable, slightly used vehicle often costs far less than a brand-new model.
- Increase your down payment. More money upfront means a smaller loan, lower interest cost, and less risk of negative equity.
- Aim for the shortest term you can reasonably manage, ideally 36–60 months.
- Make extra payments when possible and ask your lender to apply them to the principal.
- Protect your credit score so you qualify for better interest rates.
Every dollar you save on a car loan is a dollar you can redirect toward building security—emergency savings, retirement, education, or other meaningful goals.
How to Evaluate an Offer Before You Sign
Before agreeing to any car loan, pause and gather the full picture. Do not let the dealership rush you. Take the numbers home if necessary and evaluate them calmly.
Ask yourself and the lender these key questions:
What is the total amount I will repay, including interest and fees? How long will I be making payments? Can I still meet my other priorities—saving, investing, paying down other debts—while carrying this loan?
It can help to run the loan terms through an online calculator or spreadsheet. Seeing the total cost over time makes it easier to resist the temptation of a seductive low monthly payment.
Building a Healthier Relationship with Cars and Debt
The car you drive can support your life—or quietly sabotage your finances. Long-term loans, by making expensive vehicles feel affordable, often push people toward choices that do not serve their long-term interests.
Shifting your mindset from “How low can I get the payment?” to “How can I minimize total cost?” is one of the most powerful moves you can make. It transforms car buying from a stressful negotiation into a deliberate, values-based decision.
When you choose a reasonably priced car, secure a shorter loan term, and avoid unnecessary upgrades, you are not depriving yourself. You are buying something far more valuable than leather seats or a bigger engine: you are buying future freedom and financial resilience.
In the end, a car is a tool, not a trophy. Let your next loan reflect that truth. Focus on total cost, protect yourself from long-term debt, and use your money to build a life that feels rich in freedom, not just filled with payments.