The Hidden Costs of Car Loans: Fees, Add-Ons, and Traps to Avoid
Buying a car is exciting, but the way you finance it can quietly drain your wallet for years. Many people focus only on the monthly payment and ignore the true total cost of the loan. That’s where lenders, dealers, and finance companies can slip in extra fees, add-ons, and traps that make your car far more expensive than it seems.
Understanding these hidden costs can help you protect your money, negotiate better, and avoid debt that feels impossible to escape. With a bit of knowledge and preparation, you can keep control of your car purchase instead of letting the financing control you.
Why Car Loans Are So Confusing
Car loans are often sold in a way that benefits the lender and dealer, not the buyer. Instead of clearly explaining how much you will pay over time, they focus on low monthly payments and special offers that sound attractive but hide the real price.
Many buyers don’t realize that a small difference in interest rate or a few added fees can add thousands of dollars to the final cost. That’s why it’s essential to look beyond the payment and understand how car loans really work.
Key Parts of a Car Loan You Must Understand
Before diving into hidden costs, you need to know the main elements of a car loan. These basic terms are the foundation of any offer you see at a dealership or bank.
| Term | What It Means | Why It Matters |
|---|---|---|
| Principal | The amount you borrow to buy the car, not including interest or fees. | Higher principal means more interest over time. |
| Interest Rate (APR) | The cost of borrowing expressed as a yearly percentage. | Even a small rate increase can add major cost. |
| Loan Term | How long you have to repay the loan (e.g., 48, 60, 84 months). | Longer terms lower payments but raise total cost. |
| Fees | Extra charges by the lender or dealer. | They can significantly inflate your loan balance. |
Once you understand these pieces, it’s easier to see where hidden costs are being added and how to question them.
The Most Common Hidden Fees in Car Loans
Some fees are normal, but others are inflated or unnecessary. Always ask what each fee is for and whether it’s required. Here are the most common ones to watch.
- Document (doc) fees: Dealers charge this for preparing paperwork. Some regions cap these fees, but others do not, so they can be extremely high. You may not be able to remove this fee entirely, but you can often negotiate a lower vehicle price to offset it.
- Acquisition or administrative fees: These are often vague charges that sound official but may simply be extra profit for the dealer or lender. If the explanation is unclear, push back or ask for them to be removed.
- Loan origination fees: Some lenders charge a percentage of the amount you borrow just to set up the loan. This can be hundreds of dollars added to your principal, increasing what you pay interest on.
- Prepayment penalties: This fee charges you for paying your loan off early. It exists to protect the lender’s interest profits and can trap you in a bad loan. Always ask in writing if your loan has a prepayment penalty before signing.
Any time you see a fee you don’t understand, slow down. Do not sign until you’ve had a clear, written explanation. Pressure to sign quickly is often a red flag.
Add-Ons That Inflate Your Loan
Dealers often make more money on add-ons than on the car itself. These extras are usually rolled into your loan, so you pay interest on them for years.
Common add-ons include:
- Extended warranties: These can provide useful protection, but many are overpriced or cover very little. The same coverage is often cheaper when bought directly from a third party or even from the manufacturer later.
- Gap insurance: This covers the difference between what you owe and what the car is worth if it’s totaled. Gap coverage can be wise in some cases, but dealers typically charge far more than insurance companies do.
- Paint protection, rustproofing, or fabric guard: These “protection” packages are often little more than simple treatments sold at a huge markup. They add cost without increasing the car’s real value.
- Service contracts and maintenance plans: Prepaid service can be convenient, but only if you understand exactly what is covered, for how long, and whether you are likely to use it.
Each of these add-ons might be presented as a small extra per month, but when stretched across a long loan, they can become very expensive. Always ask for the total additional cost, not just the monthly impact.
Traps Hidden in Long-Term Loans
One of the biggest modern traps is the very long loan term, such as 72 or 84 months. On paper, it looks great: a lower monthly payment that makes a more expensive car seem affordable.
But the trade-offs can be harsh:
First, you pay far more in interest over the life of the loan. Even if the rate is the same, stretching the term means more months of interest.
Second, you’re more likely to be upside down on your loan, meaning you owe more than the car is worth. This creates serious problems if you need to sell, trade in, or if the vehicle is stolen or totaled.
Third, long-term loans can tempt you into buying a car that’s more expensive than you truly can afford. The low payment hides the size of the debt, which can squeeze your budget and increase financial stress.
How Dealers Manipulate Monthly Payments
Many dealerships train their sales staff to focus your attention on monthly payment instead of price, rate, or total cost. This allows them to keep you in the dark about the true numbers.
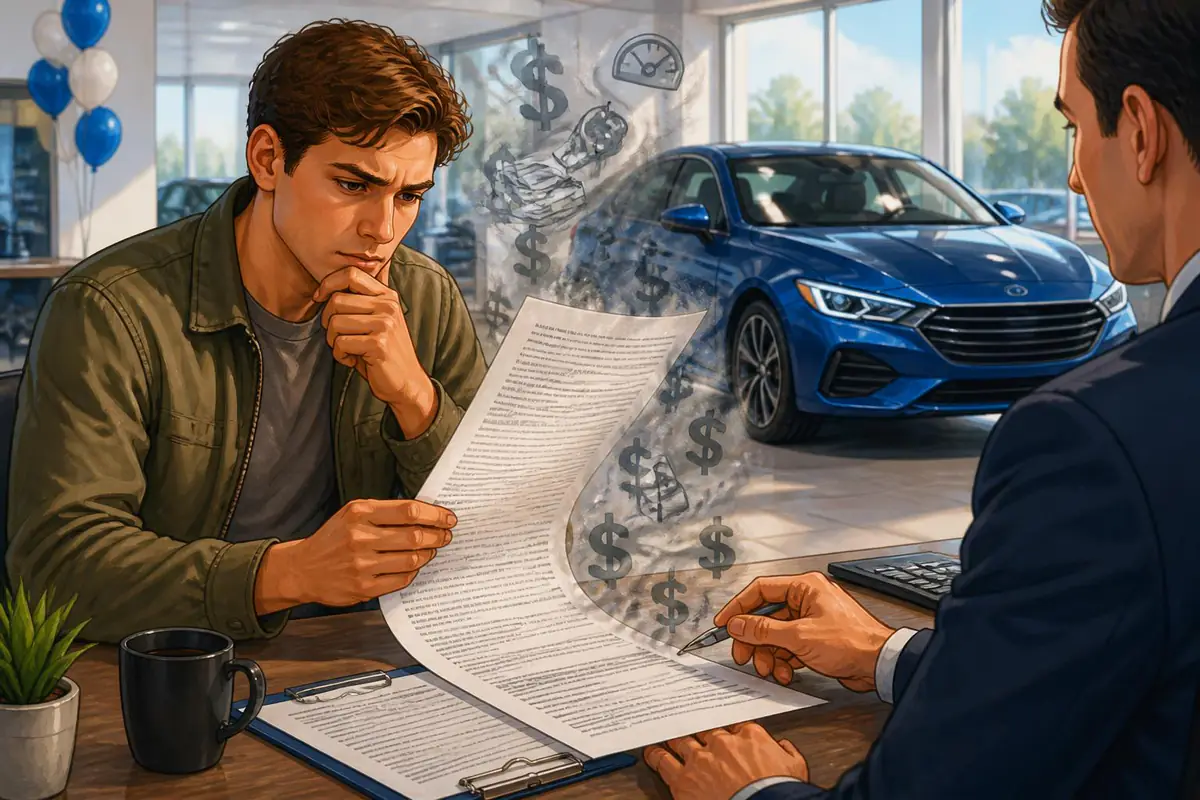
They might stretch the loan term, add unnecessary products, or increase the price of the car while keeping your payment barely within your comfort zone. You walk away thinking you got a deal when you’ve actually accepted a very costly structure.
To protect yourself, always negotiate the purchase price of the car first, completely separate from any financing. Only after you’ve agreed on a price should you discuss loans and payments.
Practical Steps to Avoid Hidden Costs
You don’t need to be a finance expert to avoid these traps. You just need a plan and the confidence to slow things down and ask questions.
Before you go to the dealership:
- Check your credit score and clean up any errors if possible.
- Get pre-approval from a bank or credit union so you know what rate you qualify for.
- Decide your maximum total budget for the car, not just the payment.
At the dealership:
Negotiate the vehicle price first, then compare the dealer’s financing offer to your pre-approval. Never be afraid to walk away if you feel rushed or confused. A fair deal will still be there tomorrow.
Ask for an itemized breakdown of every fee and add-on in the contract. Cross out anything you don’t want or that you don’t fully understand. Remember: if it’s optional, you are allowed to decline it.
Signs You Should Walk Away
Sometimes the smartest financial move is simply to say no and leave. Watch for warning signs like:
• Refusal to give you a clear breakdown of costs.
• Pressure to sign “today only” offers.
• Claims that add-ons are required for financing when they are not.
• Changing numbers between what was discussed and what appears in the contract.
If any of these occur, trust your instincts. You can always find another car or lender, but it’s much harder to escape a bad car loan once you’ve signed.
Taking Control of Your Car Financing
A car loan doesn’t have to be a trap. When you understand how fees, add-ons, and loan structures work, you can make choices that protect your future instead of undermining it.
Slow down the process. Ask questions. Compare offers. Say no to products you don’t need. Focus on the total cost rather than just the monthly payment. These simple steps can save you thousands of dollars and years of stress.
In the end, a car should make your life easier, not weigh you down with hidden debt. By spotting the tricks behind car loans and standing firm in your decisions, you can drive away with both a vehicle you like and a financing plan that truly fits your life.