What to Do With Extra Cash: Pay Off Debt, Invest, or Save?
Finding yourself with extra cash feels great — but it also raises a tough question: what is the smartest move now? Should you pay off debt, start investing, or boost your savings?
The best answer depends on your current situation, your goals, and your tolerance for risk. With a clear framework, you can turn that surplus money into a powerful tool for long-term stability and freedom.
Step 1: Get Clear on Your Financial Snapshot
Before deciding what to do, you need a simple picture of where your money stands today. This doesn’t require complex software — just honesty and a calculator.
Write down your:
- Monthly income (after tax)
- Essential expenses (housing, food, utilities, transport)
- Non-essential spending (subscriptions, eating out, shopping)
- Debts (balance, interest rate, minimum payment)
- Current savings and investments
This snapshot reveals whether your extra cash is truly “extra,” or if it needs to cover gaps like overdue bills or unstable income. If you’re behind on basics, catching up comes before any strategy.
Step 2: Protect Yourself First With an Emergency Fund
Before you pour money into investments or even aggressive debt payoff, ask one question: Could I handle a sudden surprise like a medical bill, car repair, or job loss?
An emergency fund is your financial shock absorber. Without it, a single crisis can push you back into high-interest debt — undoing months or years of progress.
Common emergency fund targets:
- Starter fund: $500–$1,000 if you’re just beginning
- Core safety net: 3 months of essential expenses
- Full cushion: 6+ months if your income is variable
Keep this money in a safe, easily accessible account, like a savings or money market account. The goal is not high returns; it’s stability and fast access.
If you don’t have at least a starter fund, a significant portion of your extra cash should go toward building it before anything else.
Step 3: Understand the Real Cost of Your Debt
Debt decisions become easier when you look at interest rates. Every dollar of interest you pay is money that could have been growing for you instead.
Make a table of your debts with these columns:
| Debt Type | Balance | Interest Rate | Minimum Payment |
|---|---|---|---|
| Credit Card A | $3,000 | 22% | $90 |
| Personal Loan | $5,000 | 12% | $140 |
| Student Loan | $15,000 | 5% | $160 |
High-interest debt (often credit cards and some personal loans) grows fast and quietly eats your future income. If you’re paying 20% interest, paying that off is like getting a guaranteed 20 percent return on your money — with zero market risk.
As a rule of thumb:
- 15%+ interest: Top priority to pay down
- 7–15% interest: Strong candidate to reduce aggressively
- Under 7%: You might balance payoff with investing, depending on goals
Step 4: When Paying Off Debt Should Come First
Paying down debt gives you a risk-free and guaranteed benefit. It can also improve your mental health, reduce stress, and increase your monthly cash flow.
Payoff should usually be your top use of extra cash if:
- You have high-interest credit card balances
- You’re only making minimum payments and balances never shrink
- Your debt keeps you awake at night or limits basic choices
Two common payoff strategies:
Debt avalanche: You pay extra toward the highest-interest debt while paying minimums on others. Once one is gone, you roll that payment into the next highest rate. This saves the most money over time.
Debt snowball: You pay extra toward the smallest balance first, regardless of interest. Each quick win builds momentum and motivation.
You can mix both: focus on high interest, but still aim for an early small win if you need a psychological boost.
Step 5: When Investing Might Be the Best Use
Once high-interest debt is under control and you have some emergency savings, investing lets your money grow faster than inflation over time. Delaying investing can be costly, because you lose years of potential compounding.
Investing often deserves priority if:
- You’ve only got low-interest debt (like some student loans or mortgages)
- Your employer offers a 401(k) match or similar benefit
- You already have a basic emergency fund in place
If your employer matches retirement contributions, that match is essentially free money added instantly. For many people, contributing enough to get the full match should come before extra payments on low-interest debt.
Common starting points for investing:
Retirement accounts like 401(k), 403(b), or IRA accounts provide tax advantages and are ideal for long-term goals. Broad, low-cost index funds or diversified exchange-traded funds (ETFs) are often a simple, effective way to participate in market growth without picking individual stocks.
Step 6: The Power of Saving for Short-Term Goals
Not every dollar needs to go to debt or long-term investments. Saving for near-term goals protects you from needing to borrow again later.
Examples of smart short-term savings goals:
- Next year’s vacation or holidays
- Car replacement or major repairs
- Moving costs or rental deposit
- Career development courses or certifications
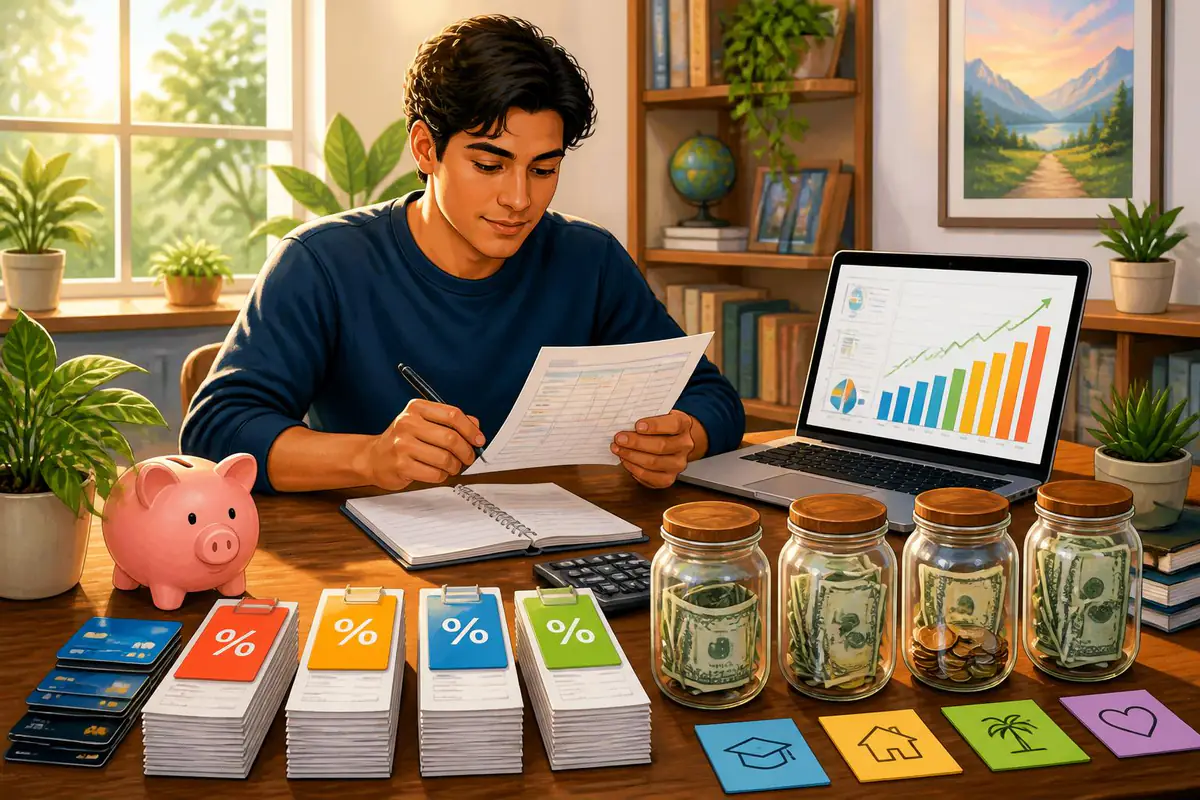
Use separate savings “buckets” (or labeled accounts) so you can see progress clearly. Watching your balance grow for a specific purpose can be highly motivating and reassuring.
Step 7: Building a Simple Priority Plan
With all these options, it helps to create a simple order of operations for your extra cash. Here is a common, flexible framework you can adapt:
1. Catch up on any overdue bills and essential needs.
2. Build a starter emergency fund (e.g., $1,000).
3. Get any available employer retirement match.
4. Attack high-interest debt aggressively.
5. Grow your emergency fund to 3–6 months of expenses.
6. Invest regularly for long-term goals (retirement, future home, etc.).
7. Pay down lower-interest debt faster and save for big purchases.
You can adjust the percentages, but having a clear sequence prevents decision paralysis and helps you stay consistent even when motivation dips.
Step 8: Use a Percentage-Based Approach for Balance
Sometimes you don’t need an all-or-nothing decision. You can split your extra cash between priorities in a way that fits your values.
For example, if you have $500 extra each month, you might choose:
$250 to high-interest debt payoff
$150 to investing for retirement
$100 to short-term savings goals
This blended approach lets you reduce debt while still building assets and preparing for upcoming needs. It also keeps you engaged, because you see progress on multiple fronts.
Step 9: Emotional Factors Matter More Than You Think
Money decisions aren’t purely mathematical. The “best” choice on paper might fail if it ignores your mindset and emotions.
Ask yourself:
- Will this choice lower my stress, or increase it?
- Do I feel more energized by crushing debt or growing investments?
- What will make me most likely to stick with the plan long term?
For some people, quickly becoming debt-free creates a strong sense of control and personal freedom. For others, seeing an investment account climb is more motivating than watching debt shrink.
As long as you’re not ignoring dangerous high-interest debt, it’s okay to lean toward the path that keeps you consistent and confident.
Step 10: Turn Extra Cash Into a Habit, Not a Surprise
The real power comes when “extra cash” stops being random and starts being planned. You can create extra on purpose by:
- Tracking spending and cutting low-value expenses
- Automating transfers to savings and investments
- Sending every raise or bonus to your priorities
Set up automatic payments or transfers on payday so you never have to decide repeatedly. This reduces temptation and ensures your money follows your priorities, not impulse.
Over time, even modest amounts add up. A consistent $200 per month toward debt, savings, or investing over several years can transform your options, reduce anxiety, and open doors you cannot yet see.
Bringing It All Together
There is no single universal answer to whether you should pay off debt, invest, or save. There is, however, a best answer for your current life and goals. Start by protecting yourself with an emergency fund, then tame high-interest debt, and finally build a future through consistent investing and thoughtful saving.
Your extra cash is more than just money — it is a chance to design your next chapter. Even small, intentional choices today can create a future where your money supports your values, your freedom, and your peace of mind.