Fixed vs Variable Rate Loans: Which Type of Interest Is Best for You?
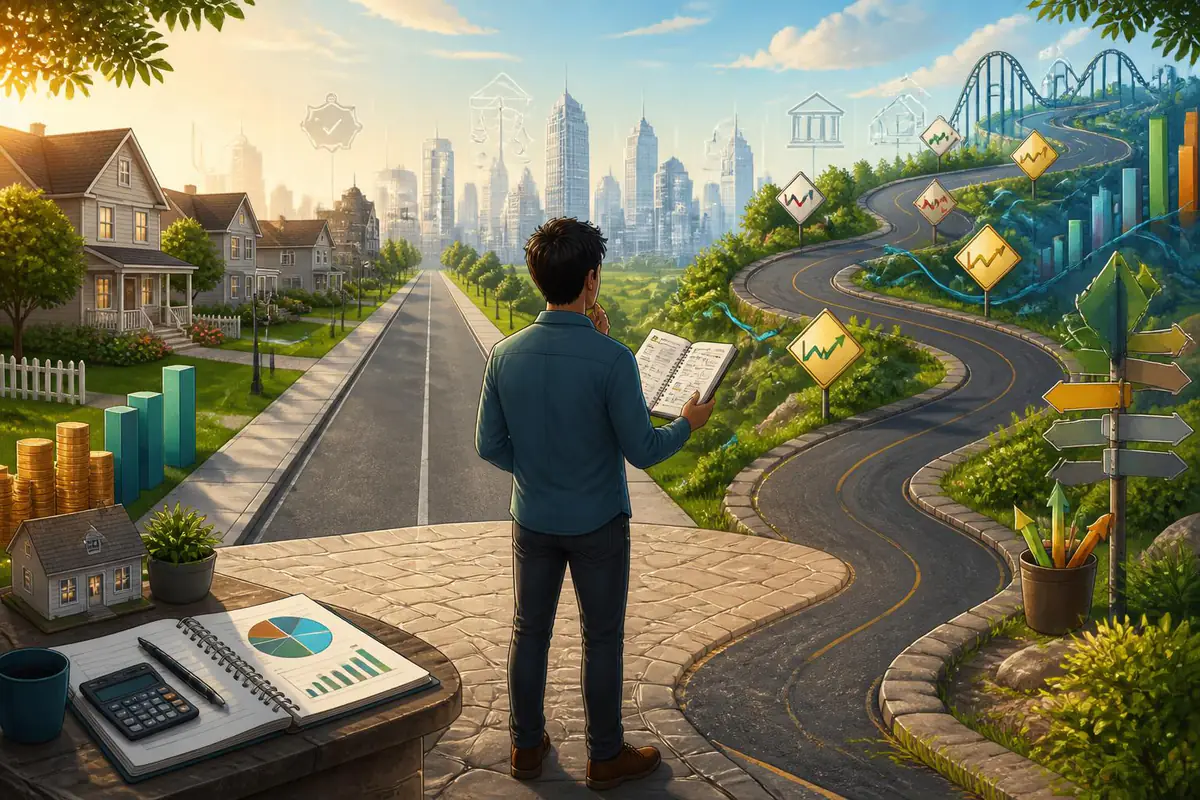
Choosing between a fixed and a variable rate loan can shape your financial future for years. The interest type you select affects your monthly payments, your total cost, and how much stress you feel whenever markets move.
Instead of guessing or following what friends did, you can make a smarter choice by understanding how each option works and how it fits your life, goals, and risk tolerance. When you align your loan structure with your personality and plans, you gain more control over your money and reduce unnecessary anxiety.
What Is a Fixed Rate Loan?
A fixed rate loan has an interest rate that stays the same for a set period, often the entire term or at least for several years. That means your interest rate and usually your monthly repayment do not change, regardless of what happens to market rates.
With a fixed rate, you know from day one how much you will pay each month, and you can project your total interest cost more easily. This predictable and stable repayment pattern is the main attraction of fixed rates.
Fixed rate loans are common for mortgages, personal loans, and car loans. Some products fix the rate for the entire life of the loan; others offer a fixed period (for example, 3 or 5 years) and then convert to a variable or adjustable rate afterward.
What Is a Variable Rate Loan?
A variable (or floating) rate loan has an interest rate that can move up or down over time. The rate is usually linked to a benchmark, such as a central bank rate, a market index, or a lender’s base rate, plus a margin.
When markets move, your rate and your repayment can change. In a falling rate environment, your monthly costs may gradually decrease; in a rising rate environment, you may pay more. This makes variable loans less predictable but sometimes cheaper over the long term.
Variable rate structures are common in home loans, lines of credit, and some business loans. They tend to suit borrowers who are comfortable with fluctuations or who have enough financial buffer to absorb increases.
Key Differences Between Fixed and Variable Rates
To decide which is best for you, it helps to compare the main dimensions where fixed and variable loans differ. Thinking in these categories clarifies not only the numbers but also how the loan will feel in your day‑to‑day life.
| Aspect | Fixed Rate Loan | Variable Rate Loan |
|---|---|---|
| Monthly payments | Stay the same during fixed period | Can rise or fall with interest changes |
| Predictability | High; easy to plan budgets | Lower; payments may fluctuate |
| Initial interest rate | Often slightly higher | Often slightly lower at the start |
| Risk of rate rises | Lender bears most rate risk | Borrower bears the rate risk |
| Flexibility | May have limits on early repayment | Often more flexible for extra payments |
| Best for | Stability and clear long‑term planning | Potential savings and flexibility |
Advantages of Fixed Rate Loans
The main advantage of fixed rate loans is certainty in your repayments. You know exactly what you will owe each month during the fixed period, which makes it easier to create and stick to a budget, plan savings, and manage other goals.
Fixed rates are especially helpful if you are in a stage of life where your expenses are rising: maybe you are starting a family, paying school fees, or building a business. Removing one major source of uncertainty can be a huge relief.
Another benefit appears when interest rates rise. If you fixed your rate before an upswing, your repayments stay unchanged while new borrowers face higher costs. In that scenario, a fixed rate feels like insurance against sudden hikes in the economy.
Fixed loans also help people who know they are uncomfortable with financial volatility. If changes in your bills cause real stress, the emotional benefit of stability may matter more than the possibility of slightly lower costs with a variable rate.
Disadvantages of Fixed Rate Loans
Despite the comfort, fixed rates are not perfect. One limitation is that the starting rate is often higher than the comparable variable option. You pay a kind of premium for the stability you receive.
If interest rates in the market fall, you may be stuck paying more than new borrowers. Refinancing or breaking a fixed contract can sometimes involve hefty early repayment penalties, which reduce the benefit of switching.
Some fixed rate loans also restrict extra repayments or redraws. Lenders do this because large early payments change the economics of a fixed rate contract. This can make it harder to aggressively pay down your debt if your income increases or if you receive a lump sum.
Advantages of Variable Rate Loans
Variable rate loans usually start with a lower interest rate than fixed options, which can mean lower initial repayments. For some borrowers, this keeps cash flow manageable during tight periods such as starting a job, moving cities, or launching a small business.
When overall interest rates fall, your repayments can reduce without you needing to renegotiate the loan. This automatic benefit can save you money over time if the rate cycle moves in your favor, turning market shifts into real savings.
Variable loans also tend to be more flexible. Lenders are often more open to extra repayments, redraw facilities, or even restructuring the loan. If you plan to pay off your loan faster than required, that flexibility can significantly lower the total interest you pay.
Disadvantages of Variable Rate Loans
The biggest drawback is uncertainty. Because your rate can change, your repayment amount may increase with little notice. This risk matters if your budget is tight or if you would struggle to absorb higher monthly costs.
Variable loans also introduce emotional volatility. Every announcement from the central bank or economic headline can cause worry. If you find yourself checking news constantly and feeling stressed, a fluctuating and unpredictable repayment pattern might not be worth the potential savings.
Finally, some people overestimate their ability to handle risk. A rate rise of one or two percentage points can add a meaningful amount to monthly repayments, especially on large mortgages. Without a buffer, this can quickly strain your finances.
How to Decide Which Type Is Best for You
There is no one answer that fits everyone. Instead of asking, “Which is better?” ask, “Which is better for me, right now, given my situation and plans?” A structured way to decide is to consider your budget, time horizon, and risk tolerance.
- Budget strength: If your budget is tight, and even a modest increase in repayments would cause trouble, a fixed rate may be safer. If you have surplus income and emergency savings, you may handle variable fluctuations more easily.
- Time horizon: If you expect to hold the loan for many years, both options will go through several rate cycles. In that case, consider a mix or focus on emotional comfort. If you expect to sell the asset or refinance soon, variable may offer more flexibility.
- Risk tolerance: Are you someone who loses sleep over what you cannot control? Or do you feel comfortable with some uncertainty in exchange for possible savings? Be honest about your emotional reaction to risk, not just the math.
Also think about your career and income stability. If you work on commission, run a business, or have variable earnings, locking in a fixed repayment can balance the variability in your income. If your income is stable and you maintain a strong cash buffer, you might choose to accept rate risk in exchange for potential benefits.
Combining Fixed and Variable: A Balanced Strategy
Many lenders allow you to split a loan into fixed and variable portions. For example, you might fix 60% and leave 40% on a variable rate. This approach can blend stability with potential savings and offer a middle path if you feel torn between the two options.
With a split loan, the fixed part gives you a base level of certainty for budgeting, while the variable part lets you make extra repayments more freely or benefit from falling rates. It also spreads your risk: not all of your debt is exposed to rate rises, and not all is locked in if rates fall.
When choosing a split, think in terms of your comfort zone. Ask yourself: “What share of my repayments must be absolutely predictable for me to feel safe?” Make that portion fixed, and allow the remaining part to float with the market.
Practical Steps Before You Commit
Before signing any loan contract, take some practical actions to protect yourself. A little preparation can make the difference between a manageable commitment and a stressful burden.
- Run detailed repayment scenarios at different interest rates to see how your budget would cope.
- Check fees for early repayment, refinancing, or switching from fixed to variable or vice versa.
- Build a small emergency fund so your loan does not dominate your life during tough times.
It can also help to imagine worst‑case and best‑case scenarios. What if rates rise sharply for three years? What if they fall? How would you feel and behave under each scenario with a fixed loan and with a variable loan?
By combining clear information with honest self‑reflection, you can choose the structure that supports your goals, protects your peace of mind, and keeps you in control. The “best” loan is not the one that wins on paper, but the one that you can sustain confidently for the long run.