From Cash Stuffing to Apps: Which Budget Method Actually Works?
Trying to budget can feel overwhelming. One person swears by colorful cash envelopes, another tracks every cent in an app, and someone else just watches their bank balance and “manages by vibes.”
Choosing the right method matters, because the best system is the one you’ll actually use consistently. Different tools work for different personalities, incomes, and lifestyles.
This guide breaks down how cash stuffing, spreadsheets, budgeting apps, and hybrid systems work, plus how to choose and customize the method that’s right for you.
Why Most Budgets Fail (and How to Avoid It)
Budgets rarely fail because people are “bad with money.” They fail because the method doesn’t match their life or behavior. Common reasons:
- Too complicated to maintain daily, so you quit.
- Too rigid, so one bad week makes you feel like a failure.
- You forget to track, and the system falls apart.
- The method doesn’t fit your spending style or income type.
Any system you pick must be realistic for your attention span, energy, and habits. Your goal isn’t a perfect budget on paper; it’s a workable routine that lasts.
Cash Stuffing: The Envelope Method
Cash stuffing, also called the envelope system, means you divide your income into physical envelopes labeled by category: groceries, gas, eating out, fun, etc.
When an envelope is empty, that category is done until the next payday. No swiping, no overdrafting, no guessing.
How cash stuffing works in practice:
- Withdraw the amount of cash you plan to use for the week or month.
- Sort it into labeled envelopes (or a binder with sleeves).
- Use only that cash for each category.
- When it’s gone, you either stop spending or move money intentionally from another envelope.
Why people love cash stuffing:
• You literally feel the money leaving your hands, which makes spending more real.
• It’s incredibly effective for curbing impulse spending fast.
• There’s no tech learning curve, no logins, no syncing issues.
• Perfect for people who are visual and tactile.
Where it can fall short:
• Harder if you do most spending online or with subscriptions.
• Not ideal if you’re uncomfortable carrying larger amounts of cash.
• Can be inconvenient for busy schedules and frequent small purchases.
• Tracking long-term trends (like your 6‑month spending) is more manual.
Best for you if: You overspend easily with cards, want a reset, or need very clear boundaries around spending categories like eating out or entertainment.
Budgeting Apps: Digital Control in Your Pocket
Budgeting apps automatically track transactions and help you plan, categorize, and limit your spending. Some popular ones use a “zero-based” budget, where every dollar has a job; others just monitor and analyze your habits.
Key strengths of budgeting apps:
• Automation: Your card spending is imported and categorized (sometimes automatically).
• Visibility: You can see all accounts in one place—checking, savings, cards.
• Customization: You can create goals, alerts, and customized categories.
• Data: Over time you see patterns and can adjust realistically.
Potential downsides:
• If you hate your phone, you’ll ignore the app.
• Syncing issues or wrong categories can feel frustrating.
• Some apps push features you don’t need or paid upgrades.
• It’s easier to feel emotionally detached from transactions.
Best for you if: You mostly pay with cards, like seeing data and charts, and are comfortable with tech. Apps especially help if you want detailed tracking over months without tons of manual work.
Spreadsheets: Flexible and Fully Customizable
Spreadsheets give you total control over your budget structure. You can design your own categories, formulas, and summaries.
They’re especially useful if you like numbers or want to deeply understand where your money goes, not just follow a template.
Pros of spreadsheet budgeting:
• Completely customizable for unique incomes or irregular expenses.
• Easy to add notes, comments, and one-time adjustments.
• Can be as simple or advanced as you like.
• Great for planning long-term financial goals.
Cons to keep in mind:
• Fully manual unless you link tools or import data.
• If you skip updating for weeks, it becomes inaccurate.
• Not as convenient as pulling out your phone at the store.
Best for you if: You’re detail-oriented, enjoy organizing data, or have variable income (freelancers, commission workers) and want to plan carefully by month or project.
Hybrid Systems: Combining Cash and Digital Tools
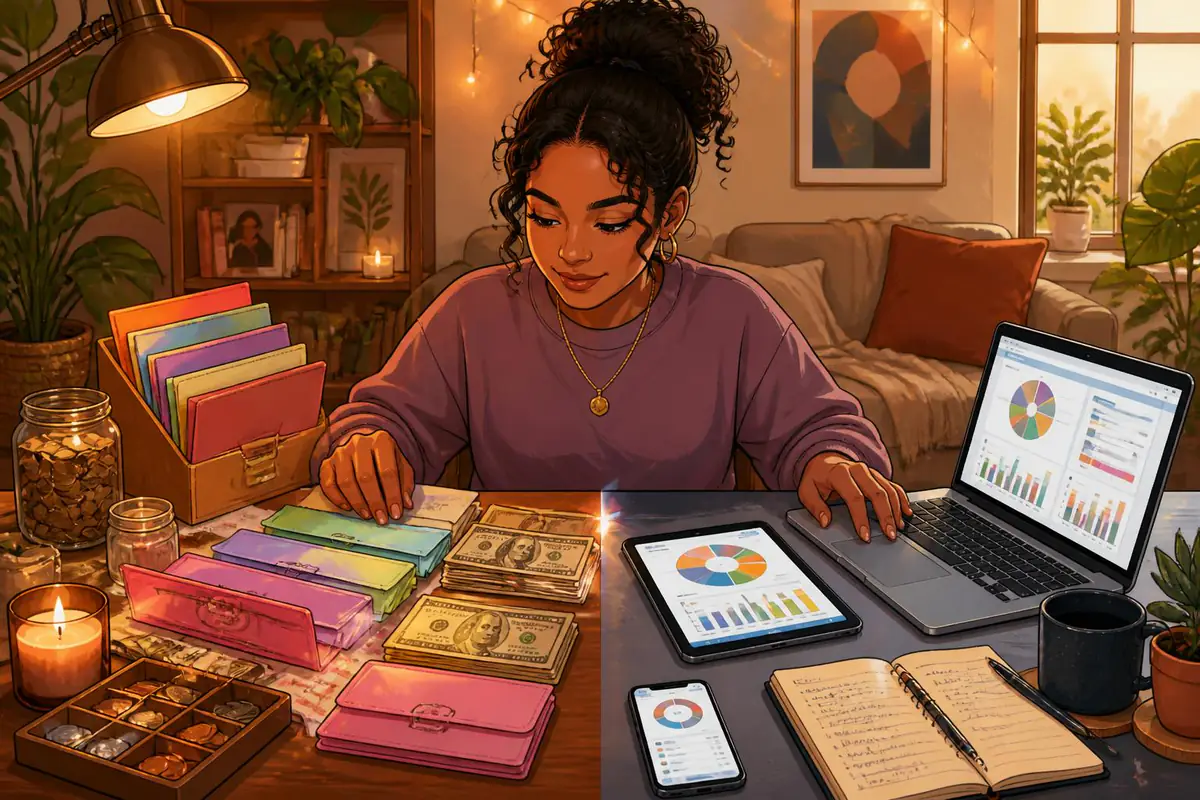
You don’t need to choose only one method. Many people succeed by mixing strategies to match how they actually live.
Some examples of effective hybrid approaches:
- Use cash envelopes only for problem categories like eating out and personal spending; track everything else with an app.
- Use a spreadsheet for the big-picture monthly plan and an app to track daily card spending.
- Keep savings goals in an app but manage regular bills with a simple written or spreadsheet budget.
The goal is to add structure where you need it most, not to overcomplicate your entire financial life.
Which Method Actually Works? Use This Comparison
The “best” method is the one you consistently follow. Use this quick comparison to decide what fits you right now:
| Method | Best For | Main Strength | Main Weakness |
|---|---|---|---|
| Cash Stuffing | Impulse spenders, beginners | Physical limits stop overspending | Inconvenient for online spending |
| Budgeting Apps | Card users, tech‑friendly | Automatic tracking and insights | Easy to ignore notifications |
| Spreadsheets | Detail‑oriented, variable income | High customization and control | Manual data entry required |
| Hybrid | Most people long‑term | Balanced flexibility and control | Can become complex if overdone |
How to Choose Your Budget Method in 10 Minutes
Use these questions to decide what to start with this month:
1. Do you overspend more with cash or card?
If cards make money feel invisible, start with cash stuffing for non‑essential categories. If cash burns a hole in your pocket, a digital method may keep you more disciplined.
2. How much time and energy do you realistically have?
If you’re exhausted or busy, you need something low‑maintenance. That likely means a simple app or minimal spreadsheet with only essential categories, not a complex color‑coded masterpiece you’ll abandon in a week.
3. Do you need a quick reset or a long‑term system?
Cash stuffing is powerful as a 1–3 month reset to build awareness. Apps and spreadsheets shine for long‑term tracking, planning, and goal setting. You can always start with one and transition to another.
Make Any Budget Method Actually Work
Once you’ve chosen a method, these habits matter more than the tools themselves:
1. Start with last month’s reality, not fantasy.
Look at your actual spending from the last 30 days and base your categories on that. If you spent $500 on food, don’t jump straight to $200. Aim for $450 instead and tighten gradually.
2. Budget every paycheck, not just every month.
If you’re paid weekly or biweekly, break your plan into each payday. Decide exactly what each paycheck covers: bills, groceries, gas, savings. This prevents mid‑month panic when money “disappears.”
3. Schedule a weekly money check‑in.
Put a 15‑minute “money meeting” on your calendar. During it, you:
- Update your app or spreadsheet or envelopes.
- Check progress toward savings or debt goals.
- Adjust categories if something unexpected came up.
This habit turns your budget from a static plan into a living tool.
4. Build in a realistic fun category.
All restriction and no fun guarantees rebellion. Add a line for guilt‑free personal spending, even if it’s small. When your brain knows there’s room for joy, you’re more likely to stay on track.
5. Expect mistakes and adjust—not quit.
You will overspend some months. That’s not failure; it’s feedback. Notice where your estimate was off, increase that category next month, and see where you can cut instead. Progress comes from adjusting, not giving up.
Evolving Your Budget as Life Changes
Your ideal method today might not be your ideal method in a year. New job, new baby, moving cities, or paying off a major debt can all change how you need to manage money.
Allow your system to evolve. You might:
• Start with cash stuffing while you build discipline.
• Shift to an app once your habits improve.
• Add a spreadsheet when you’re ready to plan bigger goals like travel, a home, or investing.
Money management isn’t about perfection. It’s about creating a simple, honest system that shows you what’s really happening and helps you direct your money on purpose.
Whether you choose cash, apps, spreadsheets, or a mix, commit to one method for the next 30 days. Learn from what works and what doesn’t, then refine. That’s how a budget stops being a punishment and starts becoming a powerful tool for the life you actually want.