Global Diversification: Why Limiting Your Portfolio to One Country Is Risky
Many investors unknowingly take a huge risk: they keep almost their entire portfolio in a single country. It feels familiar, convenient, and less scary than investing abroad. But in today’s interconnected world, this approach can quietly expose your money to dangers you do not see until it is too late.
Global diversification is not about chasing exotic opportunities. It is about reducing avoidable concentrated risk and giving your money more ways to grow. By spreading investments across different countries, sectors, and currencies, you protect yourself from local shocks and open the door to a wider range of returns.
Home Bias: The Hidden Trap in Your Portfolio
Most people suffer from something called home country investment bias. This simply means they prefer to invest mainly in their own country’s assets: domestic stocks, local bonds, national real estate, and home currency savings.
There are understandable reasons for this:
- You know local brands, companies, and news better.
- You trust your own economy more than foreign ones.
- Your employer may give you stock or pension in local funds.
- Your bank and broker promote primarily domestic products.
However, this comfort can be dangerous. When you put the majority of your wealth into one country, you tie your financial future to a single economic story. If that story changes, your savings, investments, employment, and even real estate can all be hit at once.
The Real Risks of Being Concentrated in One Country
Limiting your portfolio to one country exposes you to multiple layers of risk that can move together in the wrong direction. Understanding these risks is the first step to protecting yourself.
Economic downturn risk is the most obvious. When your country enters a deep recession, local companies may earn less, cut dividends, or even go bankrupt. If your stocks, bonds, and job are all tied to the same economy, your income and investments can fall simultaneously.
There is also political and regulatory risk. Governments can change tax rules, impose capital controls, or tighten regulations on key industries. A shift in political leadership or policy may affect entire sectors of your domestic market overnight. In extreme cases, there may be asset seizures, nationalizations, or sudden restrictions on moving money abroad.
Another major issue is currency devaluation and inflation. If your country’s currency weakens significantly against others, your international purchasing power falls. Even if local stock prices rise, you may still be losing value compared with global assets if inflation is high or your currency is falling rapidly.
Finally, there is sector concentration risk. Many countries’ stock markets are dominated by only a few industries. For example, some markets are heavy in banks, others in commodities or technology. If your local market is highly concentrated and that key sector suffers, your whole portfolio can decline sharply.
What Global Diversification Really Does for You
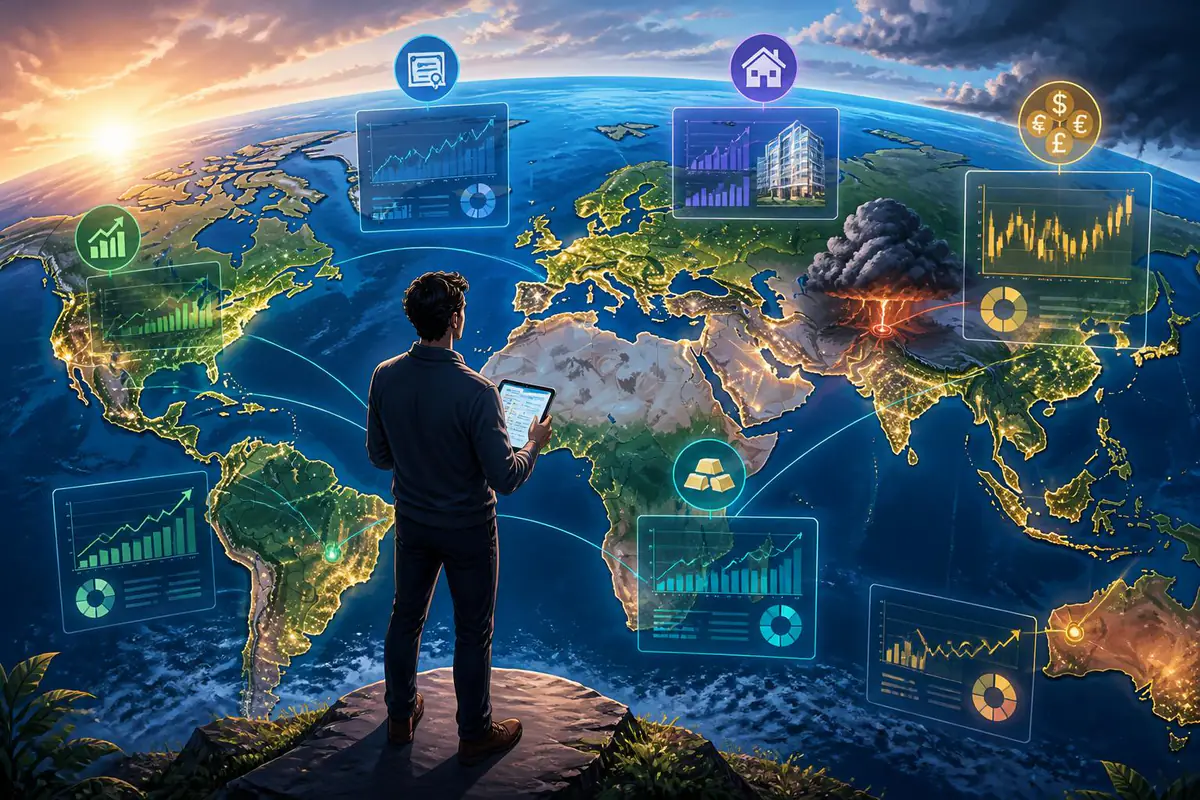
Global diversification spreads your investments across many countries and regions. The goal is to reduce the impact of any one economy, political system, or currency on your overall wealth. You are not trying to predict which country will win; you are building a structure where you do not have to guess perfectly.
Global diversification can offer three main benefits:
- Reduced volatility and smoother returns because markets do not move in perfect sync.
- Access to more growth engines, such as emerging markets and different innovation hubs.
- Protection against local crises, whether economic, political, or currency related.
For example, when one region faces a crisis, others may be stable or even thriving. Over time, global portfolios often experience fewer deep drawdowns than single-country portfolios, even if long-term returns are similar or better. That stability can make it easier to stay invested through market cycles.
Seeing the Bigger Picture: Local vs Global Exposure
To understand your own exposure, compare your country’s share of the world economy and stock markets with your portfolio allocation. Many investors discover a huge mismatch.
Consider a simple framework:
| Aspect | Home-Only Portfolio | Globally Diversified Portfolio |
|---|---|---|
| Countries included | 1 | 20–50+ |
| Currency exposure | Single currency | Multiple major currencies |
| Main risk driver | Domestic economy & politics | Global growth & broad sectors |
| Impact of local crisis | Severe and widespread | Limited to part of portfolio |
This comparison shows how a globally diversified investor is less dependent on a single story. Instead of betting your future on one country, you participate in the overall progress of the global economy.
Practical Steps to Start Global Diversification
Transitioning from a home-only portfolio to a global one does not have to be complex. You can move in stages and use simple building blocks.
First, assess your current geographic exposure. List your investments and mark which are domestic and which are foreign. Include pensions, employer stock, real estate funds, and savings products. This will show how much of your wealth depends on your own country.
Next, consider using broad global index funds or ETFs as a core component. Many low-cost funds track global or world ex‑home-country indexes, giving instant diversification across thousands of companies and dozens of countries in a single holding.
You might start with a simple structure such as:
- A global equity fund that includes developed and emerging markets.
- A bond fund with international government and corporate bonds, partly hedged to your currency if needed.
- Keeping some cash in strong foreign currencies for flexibility.
If you are heavily concentrated domestically today, you can shift gradually. For example, each time you add new money, direct it to global holdings instead of local ones. Over time, your overall mix becomes more balanced without forced selling.
How to Balance Risks When Going Global
Global diversification reduces the risk of concentration in one country, but it introduces other considerations that you should handle thoughtfully. Two of the most important are currency risk and regulatory risk.
Currency risk means that foreign investments move not only with markets, but also with exchange rates. In the short term, currencies can be volatile. To manage this, many investors:
Hold a mix of hedged and unhedged funds, focus on strong and stable currencies, and match part of their foreign bond exposure to their home currency. These steps can help maintain more stable portfolio behavior across time.
Regulatory and tax differences also matter. Different countries have distinct rules for dividends, capital gains, and fund structures. Before investing, make sure you understand the basic tax treatment and any reporting duties that apply in your situation. When in doubt, consult a qualified professional who understands cross‑border investing.
Mindset Shifts: Think Like a Global Citizen Investor
To embrace global diversification, you may need to adjust how you think about investing. Instead of seeing the world through a narrow national lens, consider yourself a global citizen of capital markets.
Here are useful mindset shifts:
Stop asking “Which country will win?” and start asking “How can I benefit from worldwide growth?” Accept that you cannot forecast perfectly which region will outperform. Instead, spread your bets intelligently so you do not depend on a single outcome.
Recognize that your life may already be overexposed to your home country through your job, property, and pension. Global investments are a way to balance that exposure and create a more resilient financial base.
Finally, focus on long-term horizons. Global diversification may not always beat your home market in every short period. But over years and decades, it can deliver a smoother journey and protect you from severe local shocks.
A Simple Action Plan You Can Start Today
You do not need advanced tools to benefit from global diversification. Begin with a clear and practical plan:
- List all your investments and estimate the percentage currently in your home country.
- Set a target range for global exposure, for example 40–70% of your equity investments.
- Choose one or two broad global funds to serve as your main international holdings.
- Redirect new contributions toward these global funds until you reach your target mix.
- Review your geographic allocation once a year and rebalance if necessary.
By following these steps, you progressively move from a vulnerable, concentrated portfolio to one that is more stable and opportunity‑rich. You shift from betting your future on a single flag to partnering with the entire world.
Global diversification is not about abandoning faith in your country. It is about accepting that any nation can face hard times and choosing not to let your entire financial future depend on one place. With a thoughtful, globally diversified portfolio, you give yourself something invaluable: greater resilience and wider possibilities for the years ahead.