How to Compare Loan Offers: APR, Fees, and Hidden Costs Explained
Choosing a loan can feel overwhelming. Every lender promises the “best rate” and “quick approval,” but the real cost of borrowing is often buried in fine print. To protect your money and peace of mind, you need to understand how to compare offers based on more than just the monthly payment.
This guide will walk you through APR, fees, and hidden costs so you can confidently choose the loan that truly costs you less in the long run.
Why the Lowest Monthly Payment Can Be Misleading
Many people focus on one question: “How much will I pay per month?” Lenders know this, so they sometimes stretch the loan over more years or tuck in extra fees to make that monthly number look attractive.
A lower monthly payment does not always mean a cheaper loan. You might end up paying more in total interest and fees over time. To find the real cost, you must look deeper at interest rate and APR together, plus every fee linked to the loan.
Interest Rate vs. APR: What’s the Difference?
The interest rate is what most ads show. It is the basic percentage you pay for borrowing the money itself. However, the interest rate alone does not tell you the full story, because it usually excludes many additional costs.
APR, or Annual Percentage Rate, is a more complete measure. It includes the interest rate plus many mandatory fees, expressed as a yearly percentage. That makes APR a powerful tool for comparing different loan offers on equal terms.
| Feature | Interest Rate | APR (Annual Percentage Rate) |
|---|---|---|
| What it shows | Cost of borrowing money only | Cost of borrowing plus many fees |
| Includes fees? | Usually no | Yes, most required charges |
| Best use | To see raw interest cost | To compare total loan offers |
| More realistic cost? | Not on its own | Yes, much closer |
When you compare loans, remember this rule: always compare APR not only interest. If one lender has a slightly higher interest rate but a much lower APR, it may still be the cheaper option overall.
The Most Common Loan Fees You Should Expect
To understand the real price of a loan, you must know which fees are involved. Some are one-time charges, others can repeat. Together, they can add up to a surprisingly large amount.
Here are some of the most common fees you might encounter:
- Origination or setup fee – A one-time fee the lender charges to process and open your loan. It is often a percentage of the total amount you borrow. Even a 2% or 3% fee can be significant on a large loan.
- Application or processing fee – Sometimes separate from the origination fee, this covers the cost of reviewing your application. In some cases it is non‑refundable, even if you are not approved.
- Underwriting or documentation fee – Charges linked to verifying your information, income, credit history, or collateral. These may appear under various names in your loan estimate.
- Late payment fee – A penalty applied when you miss a due date or pay less than the minimum required. Repeated late fees make the loan much more expensive and may hurt your credit score.
- Prepayment or early payoff fee – Some lenders charge you for paying off the loan earlier than scheduled, because they lose future interest. This fee can erase the benefit of paying your debt faster if you are not careful.
Each of these fees affects the total cost you pay. Some are included in APR calculations, some are not. Either way, you should list them clearly when comparing offers.
Hidden Costs Many Borrowers Overlook
Hidden costs are not necessarily illegal or undisclosed. Often, they are simply easy to miss if you do not ask the right questions. These extra expenses can turn a “great deal” into a poor decision.
Watch for these potential hidden costs:
- Required insurance add‑ons – Some lenders strongly “suggest” credit insurance or other policies. These may be helpful in specific cases, but they also add to your monthly payment and total cost.
- Account or service maintenance fees – You might be required to open a specific account with monthly or annual fees to qualify for a certain rate.
- Balloon payments at the end – Some loans keep monthly payments low but require a large final payment. If you cannot afford that balloon payment, you may be forced to refinance under worse terms.
- Variable interest rate changes – An initially low rate may rise over time, sharply increasing your monthly payment. Always ask whether the rate is fixed or variable.
Hidden costs are particularly common in long‑term loans, such as mortgages or auto loans, and in certain types of personal loans. Before you sign anything, ask the lender to explain in plain language every cost you will face from start to finish.
How to Compare Two Loan Offers Step by Step
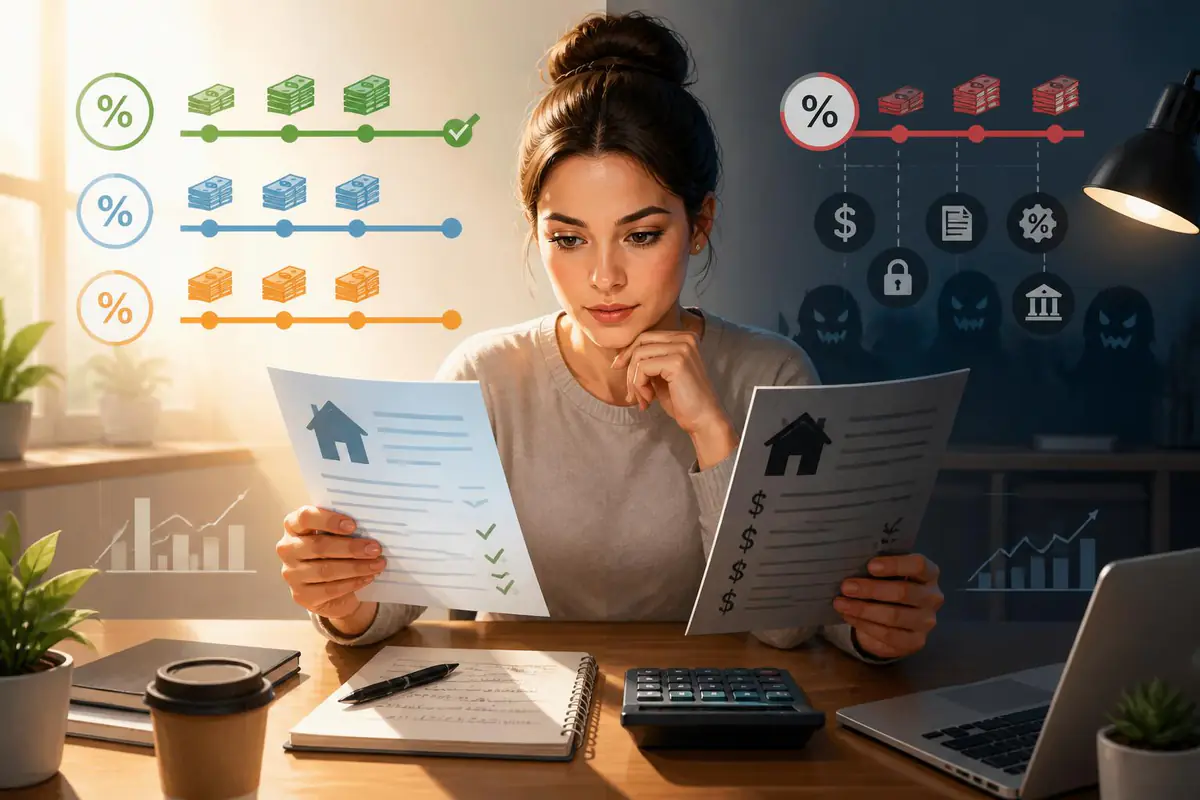
To choose the best loan, treat it like a side‑by‑side comparison. Use a simple approach that allows you to see which offer truly benefits you more.
Follow these steps for a clear comparison:
- Write down the basics of each loan: amount, term (length), interest rate, and APR. Make sure you are comparing the same loan amount and roughly the same term whenever possible.
- List all upfront and ongoing fees: origination, application, documentation, maintenance, and any mandatory insurance. Add them up to see the total extra cost.
- Calculate the total amount you will repay: multiply the monthly payment by the number of months in the term, then add any upfront fees that you pay separately. This shows the full price of borrowing.
- Check flexibility and penalties: is there a prepayment penalty? Are there harsh late fees? Can you make extra payments without being charged?
- Consider non‑financial factors: customer service quality, reputation, and how easy it is to manage the loan online or via app. These do not change the math, but they affect your experience.
Once you complete these steps for each lender, your decision becomes much clearer. You are no longer guessing. You are comparing the complete cost, not just the headline number.
Fixed vs. Variable Rates: Which Is Better for You?
A fixed rate stays the same throughout your loan term. A variable (or adjustable) rate can go up or down based on market conditions or an index. Each option has its own risks and benefits.
Fixed rates offer predictable payments and stable planning. You know exactly what you will pay every month, which helps with budgeting and reduces stress. This stability is especially valuable if you expect interest rates to rise in the future.
Variable rates may start lower than fixed rates, making them look appealing at first. However, if rates increase, your payments can rise significantly. If your budget is tight, or if you dislike uncertainty, a fixed rate may be safer even if the initial rate is slightly higher.
Practical Questions to Ask Every Lender
You do not need to be a financial expert to evaluate offers. You just need to ask clear, direct questions and write down the answers. This gives you a complete picture and makes lenders more transparent.
Use questions like these when speaking with a lender:
“What is the APR on this loan, and which fees are included in that number?”
“Besides the APR, what other costs will I pay over the life of the loan?”
“Is the interest rate fixed or variable, and if variable, how often can it change?”
“Are there any penalties or fees if I pay off the loan early or make extra payments?”
“What happens if I miss a payment? How much is the late fee, and when is it charged?”
By asking these questions, you show that you are a careful borrower. Lenders are more likely to be clear and upfront when they realize you are paying attention.
Building a Borrower’s Mindset That Protects You
Beyond numbers and formulas, comparing loans is about mindset. A strong borrower’s mindset keeps you focused on long‑term cost and financial health, not just immediate convenience.
Adopt these habits to protect yourself:
Slow down before signing anything. When you feel rushed, you are more likely to miss important details. Taking one extra day to review the loan documents can save you years of stress.
Read every line related to rates, fees, and penalties. If something is confusing, ask the lender to explain it in simple terms. You have the right to understand how your money will be used.
Regularly review your loan after you take it. Check statements, track your remaining balance, and look for opportunities to pay it off faster if there is no prepayment penalty.
When you understand APR, fees, and hidden costs, you transform from a passive customer into an informed decision‑maker. You can choose loans that support your goals instead of draining your resources. That confidence is a powerful step toward long‑term financial independence and security.