The Psychological Traps Sabotaging Your Savings (And How to Beat Them)
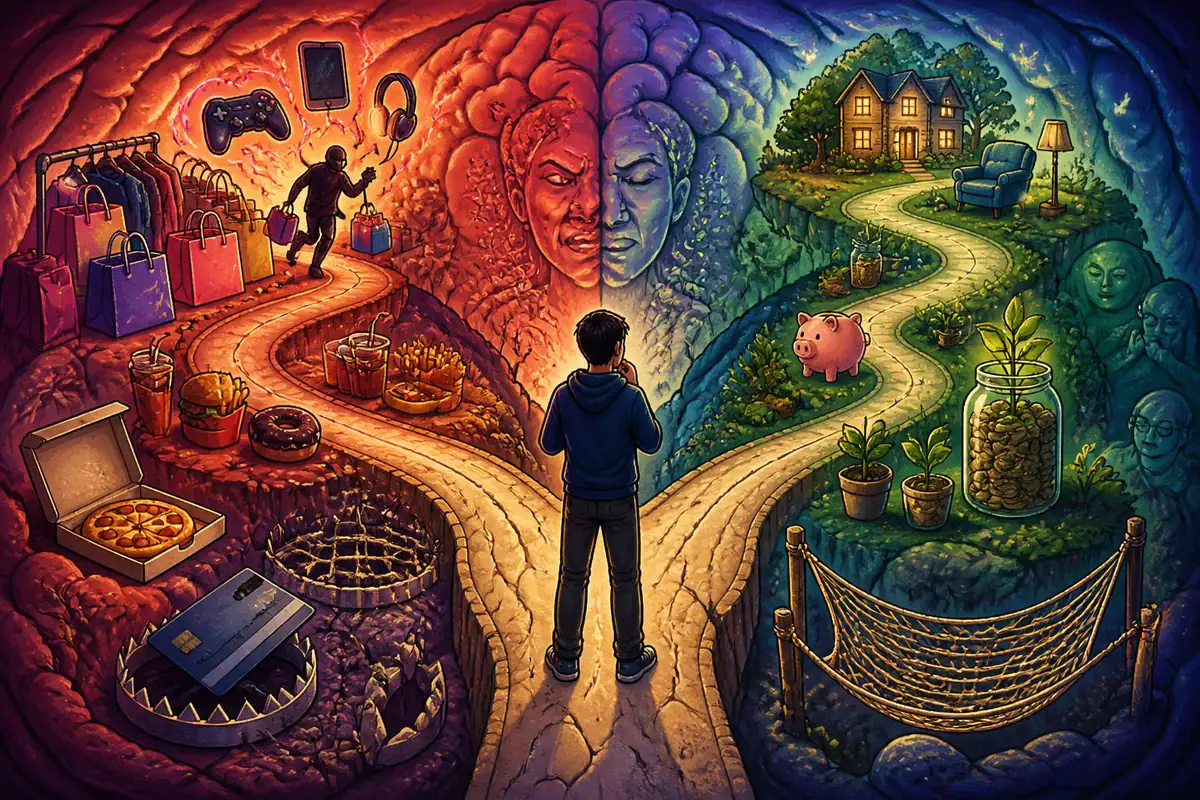
Wanting to save more money and actually saving more money are two very different things. You probably know you “should” build an emergency fund, invest for the future, or pay down debt faster. Yet months go by, and your bank balance looks almost the same.
This isn’t just a math problem. It’s a mind problem. Your brain comes with built-in biases and emotional reactions that quietly pull you away from your goals. Until you understand these psychological traps draining your savings, you’ll keep wondering why willpower never seems to be enough.
The good news: once you see these patterns, you can design simple systems to protect yourself from them. You don’t need more discipline; you need better setups.
Trap 1: Present Bias – “I’ll Start Saving Later”
Present bias is your tendency to prioritize small rewards right now over bigger rewards in the future. Your brain feels today very vividly and tomorrow as a vague concept, so an online order or dinner out seems more real than a future emergency fund.
This is why you might think, “I’ll start saving next month, when things are calmer.” But next month never arrives, because there is always another “now” with new temptations.
To beat present bias, you must make saving the default, not a decision you revisit every payday.
- Automate transfers on payday: Set a recurring transfer to savings or investments the same day your income arrives. If you never see the money in checking, you’re less tempted to spend it.
- Use the “pay yourself first” rule: Treat savings like a bill. Instead of saving what’s left over, spend what’s left after saving.
- Reduce friction for good choices: Make saving one-click easy in your banking app. Remove stored cards from shopping sites to add friction to spending.
Think of your future self as a real person you care about. Each automatic transfer is like sending them a gift. That mental shift weakens the grip of present bias and makes consistent saving feel more meaningful.
Trap 2: Lifestyle Creep – “I Deserve This Upgrade”
When your income rises, your expectations quietly rise with it. That’s lifestyle creep. You promise yourself that a raise or bonus will go straight into savings, but suddenly you are upgrading apartments, subscriptions, gadgets, or vacations.
The real danger is that small recurring upgrades add up far more than one-time splurges. A streaming service here, a nicer car payment there, and soon your higher income disappears into a more expensive normal.
To stay ahead of lifestyle creep, build rules before the extra money arrives.
| Income Change | Suggested Savings Rule |
|---|---|
| Small raise (2–5%) | Save or invest at least half of the increase and allow the rest for lifestyle. |
| Large raise (>10%) | Automatically direct most of the new income to long-term goals before adjusting your spending. |
| Bonus or windfall | Use a 50/30/20 rule: 50% goals, 30% enjoyment, 20% debt or buffer. |
Before you change anything big, like housing or a car, pause and calculate: “If I kept my old lifestyle, how much could I save in one year?” Seeing a real number makes it harder to casually accept expensive upgrades.
Trap 3: Social Comparison – “Everyone Else Seems Ahead”
Humans are wired to compare. You see friends posting vacations, new phones, or renovations, and your brain screams, “You’re falling behind.” Social comparison can trigger status-driven impulsive spending that has nothing to do with what you truly value.
Complicating this: you’re comparing your inside to their outside. You don’t see their credit card statements, money stress, or family help. You only see the highlight reel.
To loosen the grip of comparison, you need to reconnect with your own definition of “enough” and “success.”
- Clarify your top three money goals: For example, “Emergency fund, debt-free by X date, invest Y per month.” Let these guide your choices, not other people’s purchases.
- Curate your feeds: Mute or unfollow accounts that trigger envy or impulsive shopping. Follow creators who normalize simple, values-driven living.
- Create a “joy per dollar” list: List what actually brings lasting joy: maybe travel, books, or time freedom. Spend there, cut elsewhere.
When you spend according to your own priorities, you stop chasing a moving target of status and start building a life that genuinely fits you.
Trap 4: Loss Aversion – “I Don’t Want to Feel Deprived”
Loss aversion means the pain of losing feels stronger than the pleasure of gaining. So when you consider cutting expenses or increasing savings, your brain focuses on what you are “giving up”: dinners out, new clothes, treats.
This is why strict budgets often fail. They feel like punishment. The trick is reframing savings not as deprivation, but as swapping short-term comfort for long-term security and freedom.
Practical ways to work with, not against, loss aversion:
- Rename your accounts: Instead of “Savings,” use names like “Freedom Fund,” “Future Home,” or “Stress-Free Cushion.” These remind you what you’re gaining.
- Use “not now, maybe later”: When tempted by a purchase, tell yourself you can buy it in 7 days if you still want it. Often, the urge fades, and you avoid feeling strictly forbidden.
- Trade, don’t cut: For every new recurring expense, consciously drop or downgrade another. You’re exchanging, not just losing.
Over time, your brain begins to associate saving with security, options, and calm rather than sacrifice. That emotional shift is powerful fuel for long-term change.
Trap 5: Optimism Bias – “Nothing Bad Will Happen”
Optimism bias makes you believe that bad events are less likely to happen to you than to others. Job loss, medical bills, car repairs—those are “rare surprises” in your story, even though they’re common in real life.
This bias leads to under-saving for emergencies and under-insuring against real risks. As long as life is going smoothly, it feels safe to skip building a proper safety net.
To work around optimism bias, ground your planning in reality, not hope.
Start with an emergency fund goal. Many people aim for 3–6 months of essential expenses, but if that feels overwhelming, begin smaller:
First milestone: $500–$1,000 to cover minor crises. Next milestone: one month of core bills. Keep stacking until you reach your comfort zone.
Bonus exercise: Write down three “annoying but realistic” emergencies that could hit in the next year—a major car repair, a dental procedure, a period of reduced hours at work. Ask: “If this happened tomorrow, how would I pay for it?” Let that answer guide how urgently you need to save.
Trap 6: Decision Fatigue – “I’ll Deal With Money Later”
Every decision you make during the day drains a bit of mental energy. By evening, your willpower is tired. That’s decision fatigue. When it hits, you default to whatever is easiest—often convenient but costly options like takeout, impulse orders, or ignoring your budget.
The solution is to reduce how many money decisions you must make, like putting your finances on rails.
Here are ways to do that:
- Schedule a weekly “money date”: 20–30 minutes at the same time each week to check balances, pay bills, and adjust plans. Keeping it routine lowers mental resistance.
- Pre-decide spending limits: For categories like eating out, entertainment, or shopping, decide the amount ahead of time. Use separate accounts or prepaid cards to enforce those limits.
- Standardize big decisions: For major purchases, create a rule—e.g., “Anything over $200 requires a 48-hour wait and a quick check against my goals.”
By turning recurring choices into automatic rules, you conserve willpower for when you really need it—and avoid being pushed off track by a tired brain.
Turning Insight Into Action: A Simple Saving Blueprint
Knowing the traps isn’t enough; you need a simple plan that works even on your worst days. Here’s how to put it all together in a practical way.
First, define one clear priority. Do you most need an emergency fund, debt reduction, or retirement investing? Start with just one main goal for the next three to six months. Clarity beats complexity.
Next, build an automatic system around that goal:
Set a transfer from checking to your goal account on payday. Even if it is a small amount, protect it by making it automatic. You can always increase it later, but the habit matters most at first.
Then, choose one behavior to safeguard yourself from each major trap:
For present bias, automation. For lifestyle creep, a rule for raises. For comparison, a short list of your own values. For loss aversion, renamed accounts that highlight what you gain. For optimism bias, a concrete emergency number. For decision fatigue, a weekly money date.
Finally, track progress visually. Use a simple chart, note, or savings thermometer you update weekly or monthly. Seeing your savings grow turns invisible progress into visible motivation, helping your emotional brain stay engaged.
Financial success is less about being perfect and more about designing a life where the easiest path is also the smartest. When you understand the psychology that works against you, you can redesign your environment to quietly work for you.
Your brain may be wired for shortcuts and impulses, but with the right systems, you can still build savings, security, and freedom—one intentional choice at a time.